Preparing your application? Visit the service page for the next step towards an individual assessment.
Legal commentary and primary sources
The legal framework, explained in detail.
Enter a question or term and select “Search”. The complete legal commentary remains available below.
Document checklist
Your preparation checklist.
Select your pension type, qualification route and family circumstances. Open your personalised document checklist as a PDF in a new tab.
Free to use. No registration. Your selections are processed in your browser.
Your preparation list
Fischer & Cie. · Legal knowledge from Panama
The detailed legal commentary by Karen Dorcy, LL.M., Abogada on Panama’s Pensionado residence category. Requirements, evidence, procedure, costs and related questions with traceable sources.
English adaptation of the German white paper · source edition 1.0, dated 26 August 2026 · subsequent developments require separate review
WHITE PAPER
Panama Pensionado Visa
Jubilado y Pensionado
Legal framework, eligibility, procedure, costs and risks for international applicants
Karen Dorcy, LL.M.
Abogada, República de Panamá · Idoneidad No. 10179
English adaptation · source edition 1.0 dated 26 August 2026
Legal notice, scope and currency
This commentary provides general information about Panama’s Jubilado y Pensionado residence category. The original Spanish legislation, published Servicio Nacional de Migración requirements and the authority’s decision in each case are decisive. This English adaptation follows the German source edition dated 26 August 2026, with the qualifications identified here. It is not a substitute for reviewing a particular application file or checking subsequent amendments.
Legal scope. The subject is the law of the Republic of Panama. Pensionado residence is not a general work permit, tax classification, promise of bank acceptance, customs clearance or grant of citizenship. Related matters are addressed only insofar as Panamanian law and authorities are involved.
This document does not recommend whether relocation is personally or financially appropriate. It does not provide advice on foreign tax, social-security, pension, registration, succession, nationality or other law. Applicants must engage appropriately qualified advisers in the relevant jurisdictions.
The German source is authored by Karen Dorcy, LL.M., Abogada of the Republic of Panama, Idoneidad No. 10179. The commentary follows a legal sequence: governing rule, eligibility, evidence, procedure, legal consequence and risk.
Method and hierarchy of sources
Table 1 · Source hierarchy and evidential weight
| Rank | Source type | Role in the commentary |
|---|---|---|
| 1 | Legislation, Decreto Ley, Decreto Ejecutivo and Gaceta Oficial | Eligibility, thresholds, time limits, exemptions, legal consequences and limits. |
| 2 | SNM checklist and official authority guidance | Filing documents and the published administrative procedure. |
| 3 | Specialist official sources from MITRADEL, DGI, Aduanas, Tribunal Electoral or ACODECO | Employment, taxation, imports, identification and consumer matters. |
| 4 | Legal planning | Preparation, sequencing, contingencies and risk management; expressly distinguished from legislation. |
Material legal statements, deadlines, monetary thresholds and statutory concessions are linked to source references [P1] to [P25] . Market claims, blogs and relocation websites are not treated as legal authority. Unresolved matters, unconsolidated amendment chains and general portal references are identified as such.
Executive summary: eleven key conclusions
Jubilado y Pensionado is a specific permanent residence category. Article 203 as amended in 2009 and the SNM checklist provide for indefinite residence without renewal. Statutory cancellation grounds remain applicable. [P2]–[P4], [P13]
A lifetime pension or jubilación from a foreign government, international organisation or private company is required. Future entitlements, investment portfolios and fixed-term withdrawals are not equivalent merely because they serve a similar economic purpose. [P3], [P4]
The standard amount is B/.1,000 per month or the foreign-currency equivalent. Personal ownership of property in Panama worth more than B/.100,000 can reduce the threshold to B/.750; a qualifying pension remains necessary. [P3], [P4]
Under amended Article 201, private pensions require additional evidence of fund administration for the company or applicant, the existence and validity of the relevant pension-paying and fund-administering entities, and actual payment. This should not be recast as an express requirement for an actuarial certificate of full capital funding. [P4], [P13]
Spouses may combine qualifying pensions. The SNM checklist also requires B/.250 in additional monthly financial capacity per dependant. The special rule for dependent full-time students provides temporary status up to age 25. [P3], [P4]
The core file comprises passport evidence, criminal record, health certificate, personal declaration, properly authenticated foreign documents and category-specific evidence. The health certificate must have been issued within three months before filing. [P2], [P4]
An apoderado legal submits the application. Article 34 specifies up to 60 working days for a decision and 15 working days to remedy deficiencies. Its positive administrative-silence mechanism, discussed in the official interpretation for applications filed from 26 August 2009, requires separate legal assessment and formalisation; it does not itself supply a resolution or identity documents. [P2], [P23]
The general B/.250 payment to the Tesoro Nacional and B/.800 repatriation deposit under Article 28(4) are not budgeted for a regular Pensionado application: amended Article 201 expressly excludes that provision. [P2], [P5], [P13]
Residence does not determine whether a particular activity is lawful, establish tax residence or settle the source of income. Ley No. 9, the applicable MITRADEL categories and tax law require distinct but factually coordinated analysis. [P5], [P9], [P10], [P18], [P19], [P24]
Import privileges under Ley No. 9 and concessions under Ley No. 6 have their own beneficiaries, conditions and procedures. They are not an automatic package accompanying residence. [P5], [P14]–[P17]
Absence for more than two years without the necessary justification or authorisation, loss of the basis for approval, inaccurate documents or incompatible activities can affect residence. Changes require prompt review. [P2]
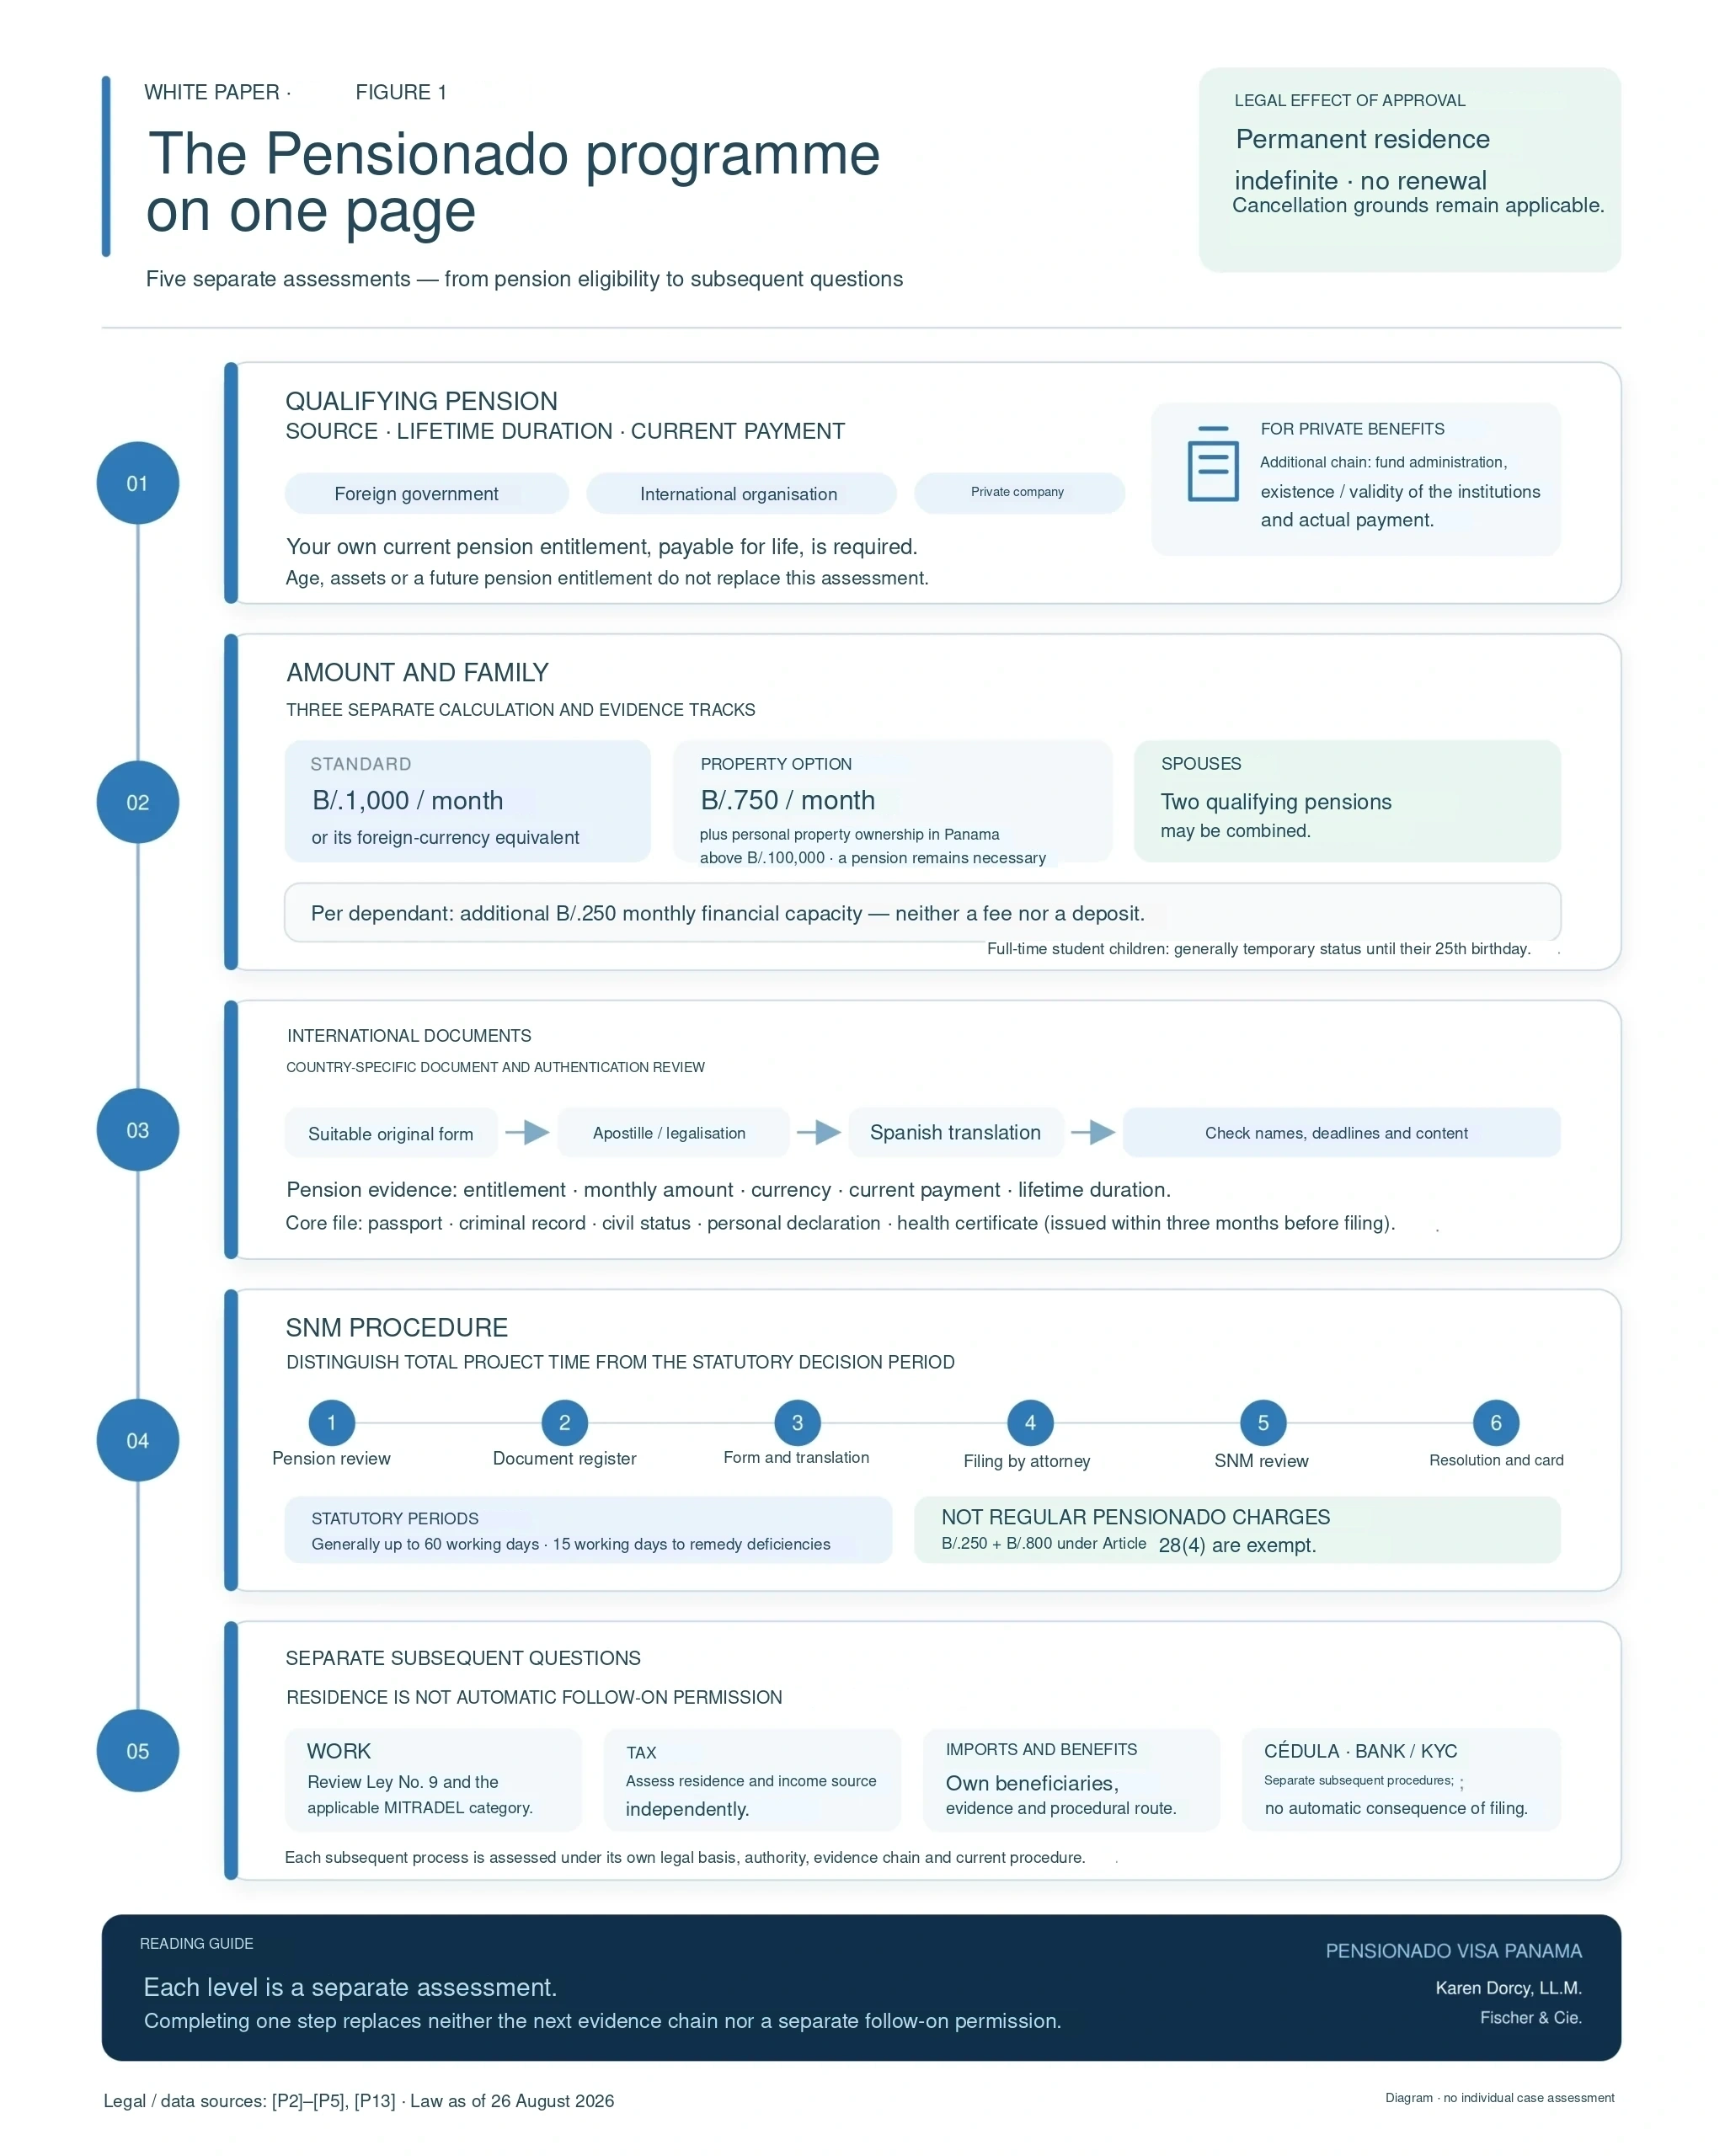
Figure 1 · The Pensionado programme at a glance
1. Legal nature, legislation and authorities
1.1 Official designation and legal effect
The regulation calls the category Jubilado y Pensionado. “Panama Pensionado visa”, “retirement visa” and “retirement residency” are common English descriptions. These are convenient terms; the original Spanish legal category governs the assessment. [P3]
The category belongs to permanent residence under special state policies. It does not begin with a multi-year preliminary status followed by an automatic conversion. Article 203, as amended by Decreto Ejecutivo No. 26/2009, provides indefinite residence without renewal. Indefinite does not mean immune from cancellation: Article 31 of Decreto Ley No. 3 remains applicable. [P2], [P13]
1.2 Development of the framework
Ley No. 9 of 1987 established the framework for foreign jubilados and pensionados, including import and immigration exemptions. Decreto Ley No. 3 of 2008 reorganised the immigration system. Articles 200–203 of Decreto Ejecutivo No. 320/2008 addressed pension sources, amounts, private evidence and family matters. Decreto Ejecutivo No. 26/2009 amended Articles 201 and 203. The SNM checklist translates that framework into filing requirements. [P2]–[P5], [P13]
Table 3 · Legislative development and present role
| Year | Source | Present role |
|---|---|---|
| 1987 | Ley No. 6 | Separate system of statutory concessions and priority rights; not a residence permit. [P14] |
| 1987 | Ley No. 9 | Foreign jubilados/pensionados, import privileges and immigration exemptions. [P5] |
| 2008 | Decreto Ley No. 3 | General immigration framework, application file, procedure, cancellation and notification duties. [P2] |
| 2008 | Decreto Ejecutivo No. 320 | Articles 200–203: sources, amounts, private pensions, property, spouses and children. [P3] |
| 2009 | Decreto Ejecutivo No. 26 | Exception from Article 28(4); indefinite residence without renewal. [P13] |
| 2023 | Decreto Ejecutivo MITRADEL No. 6 | Work-permit framework; separate from the residence decision. [P9] |
| Accessed in 2026 | SNM PRP-JP PDF without a stated revision date | Filing checklist available on the SNM website at the German edition’s review date; the access year is not an edition year. [P4] |
Editorial note: the PDF [P4] does not state an issue or revision date. An access date describes online availability when checked, not an officially designated “2026 edition”.
1.3 Responsibilities
Table 4 · Authorities and their roles
| Body | Decides or confirms | Does not establish |
|---|---|---|
| Servicio Nacional de Migración (SNM) | Pensionado residence, immigration file, decision and immigration documents. | Tax assessment, work permission or customs clearance. |
| Panamanian attorney / apoderada legal | Application, power of attorney, file management and analysis under Panamanian law. | Government approval or bank acceptance. |
| Pension provider | Entitlement, type, amount, duration and payment of the pension. | Interpretation of Panamanian immigration law. |
| MITRADEL | Work permits and employment-related immigration classification. | Grant of Pensionado residence. |
| DGI | Tax registration, residence certification and other tax procedures. | Immigration status or foreign tax consequences. |
| Autoridad Nacional de Aduanas | Import and exemption procedure. | Automatic clearance merely because a residence card is held. |
| Tribunal Electoral | Separate identity and civil-status procedures. | Replacement of the SNM decision. |
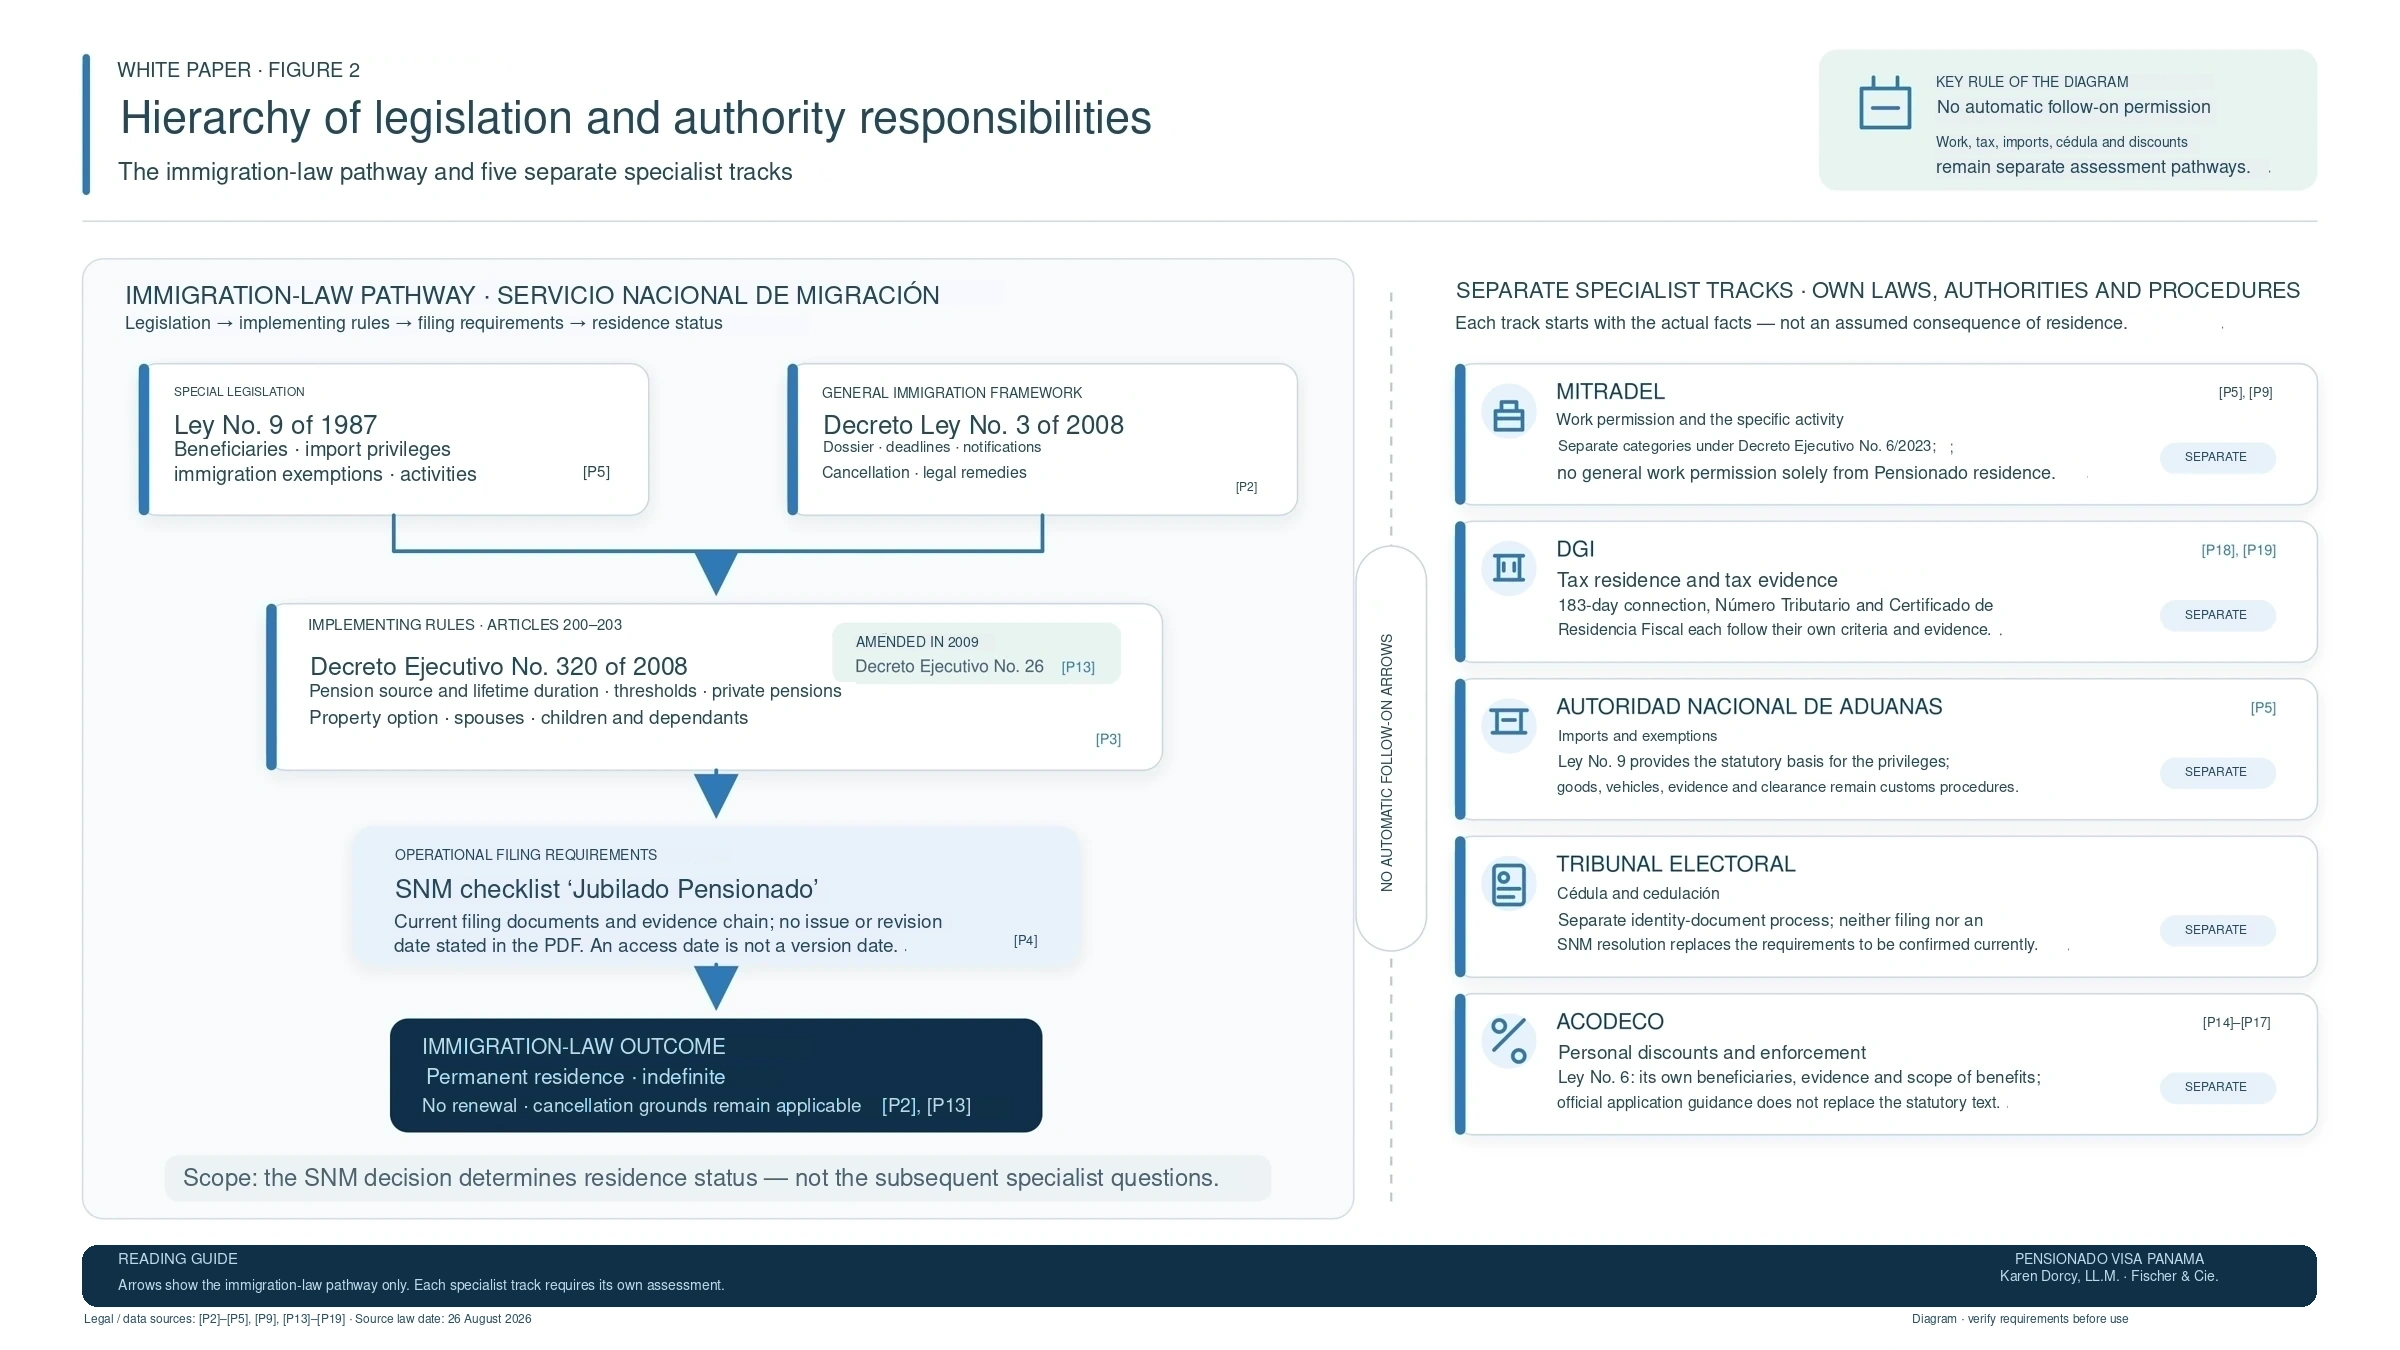
Figure 2 · Legal hierarchy and responsible authorities
2. Eligibility and qualifying pensions
2.1 The legal eligibility test
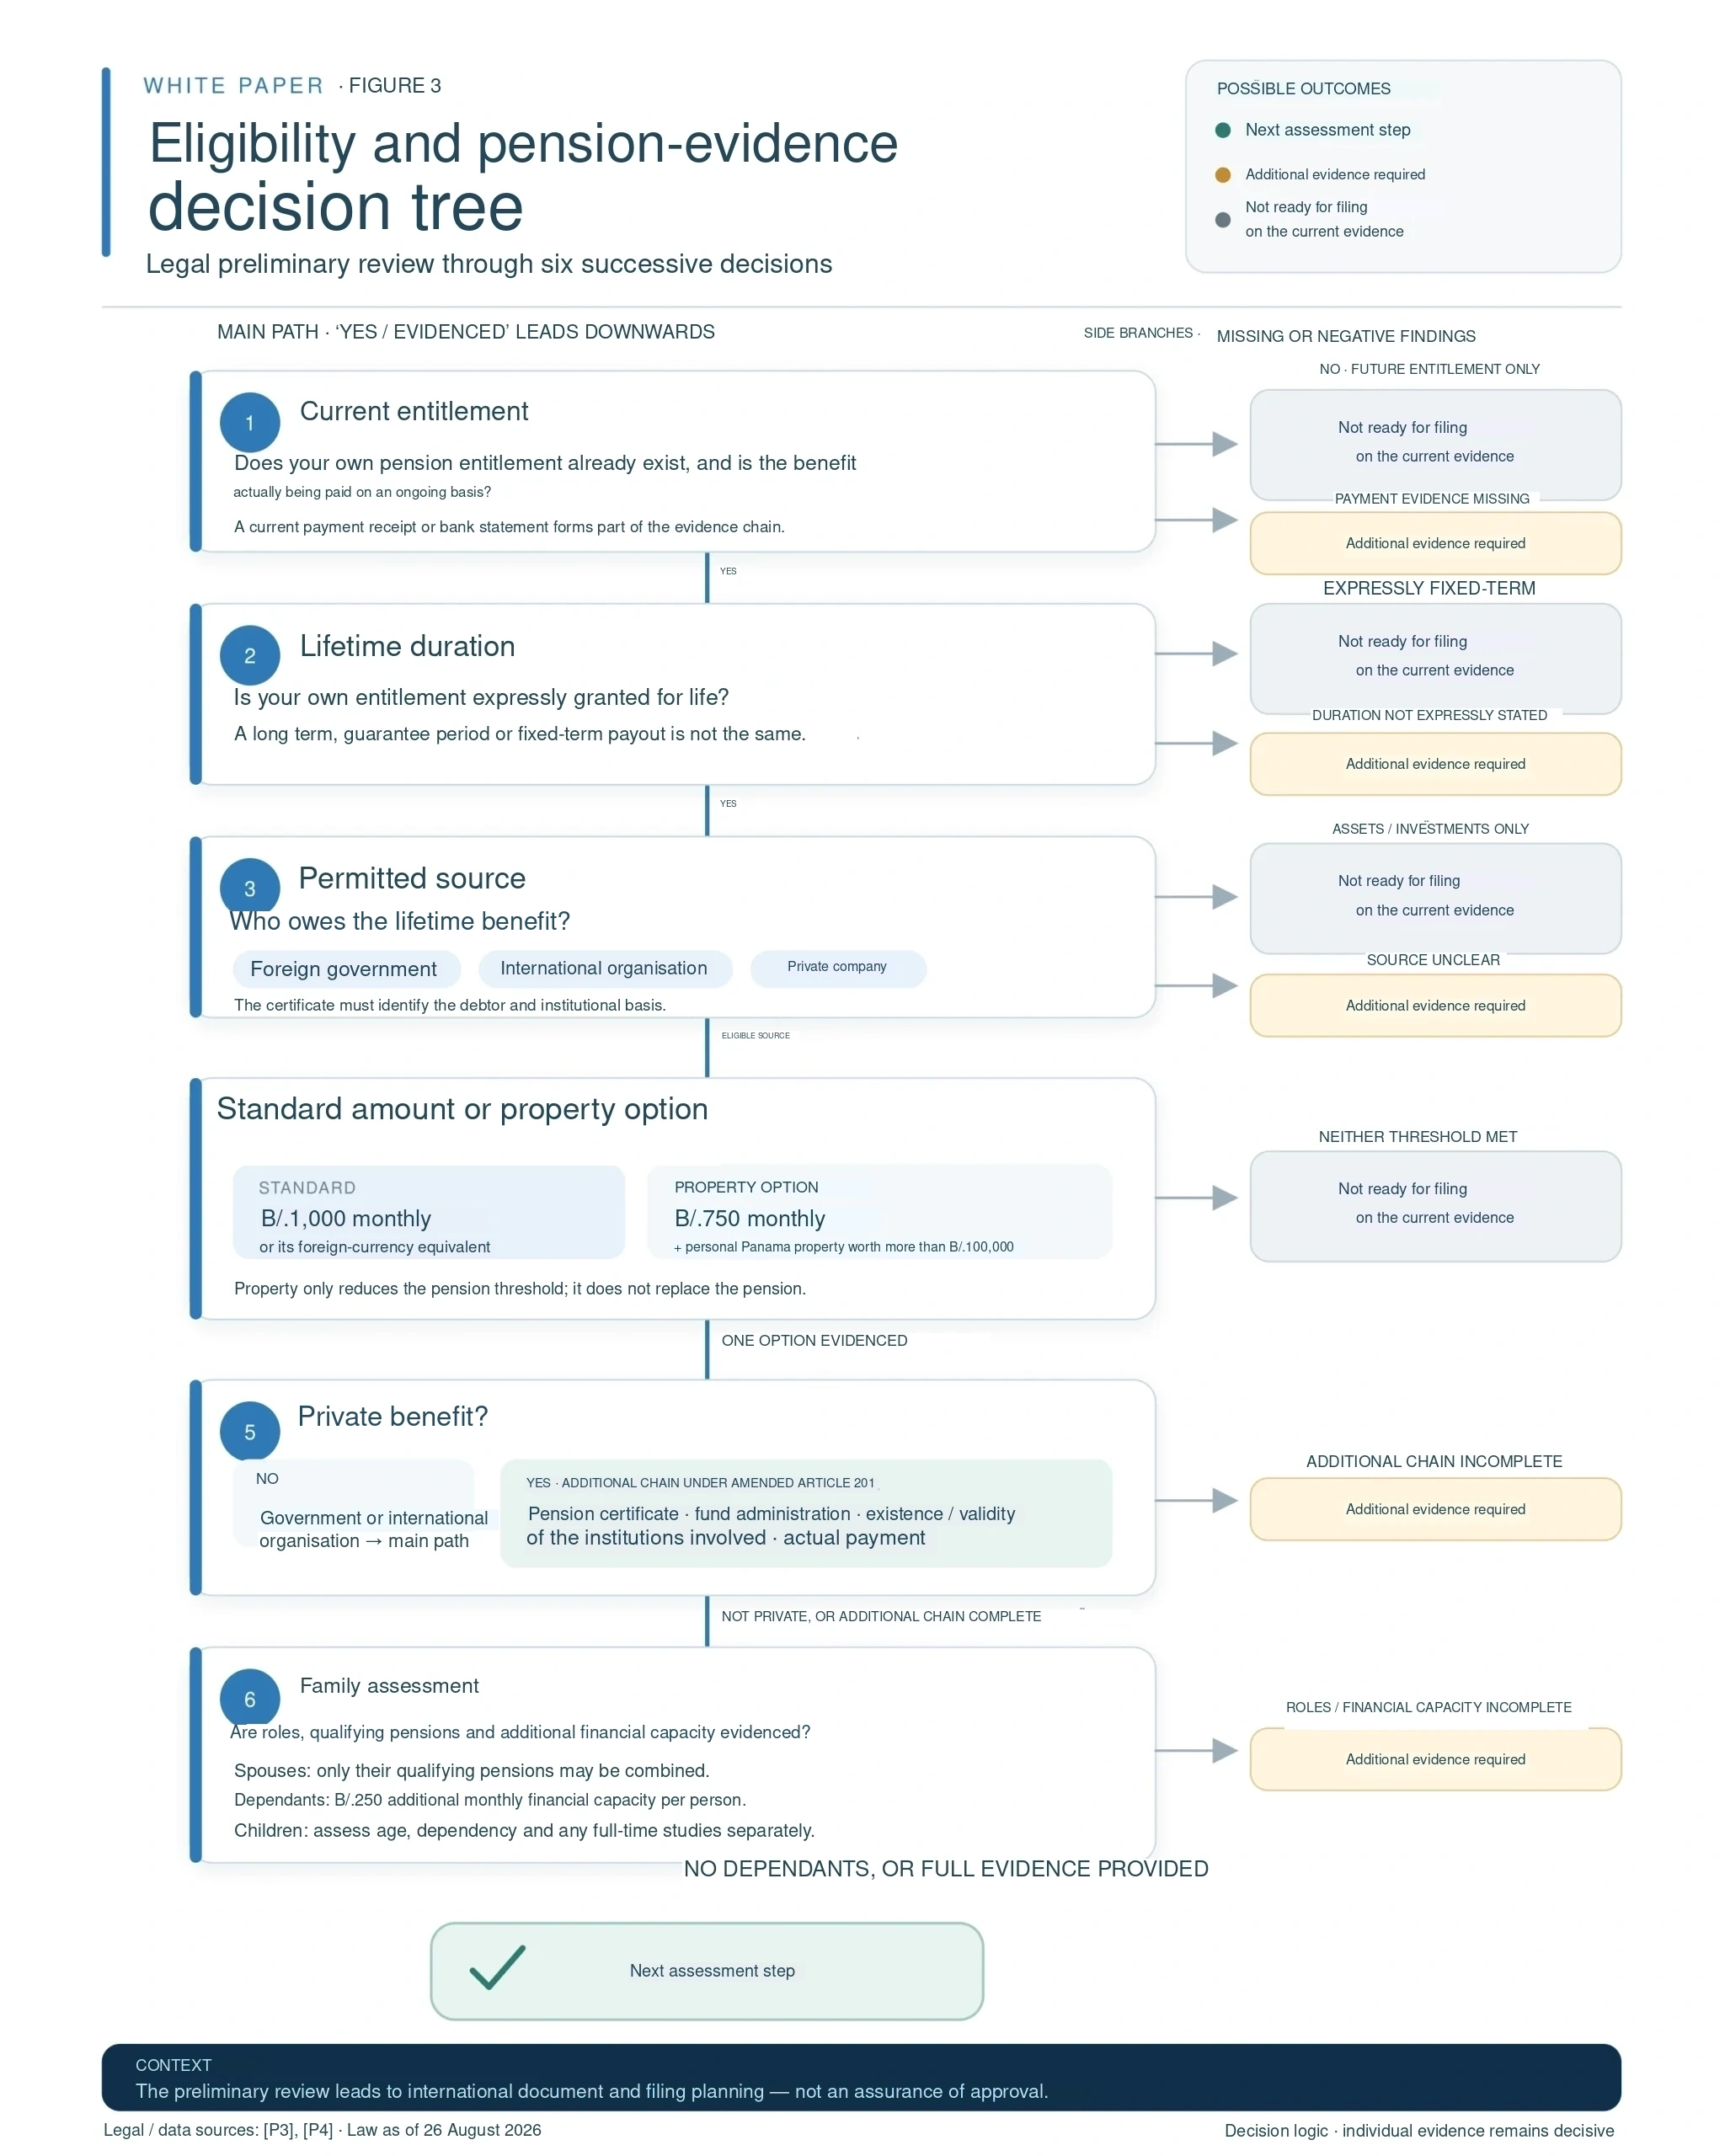
Age is not the first test. Article 200 requires a lifetime jubilación or pensión from specified sources and sufficient means for the applicant and dependants. An older applicant with only capital or a future entitlement may therefore be ineligible. Conversely, the reviewed immigration rule contains no general minimum age. [P3], [P4]
The file must answer four questions: who owes the benefit; on what legal or contractual basis; what monthly amount is paid and in which currency; and why the entitlement lasts for life. The pension award, current payment evidence and authentication chain serve different purposes.
2.2 Government and international benefits
Benefits from a foreign government or international organisation are expressly contemplated. A state retirement pension may fall within this category, but neither nationality nor a scheme’s familiar name replaces a certificate establishing the individual entitlement, amount and lifetime duration. [P3], [P4]
Survivor and disability benefits are not included or excluded merely by their label. The applicant’s own benefit must be current, sufficient and payable for life. Time limits, review mechanisms, suspension rules and termination events must be disclosed.
2.3 Private pensions
Article 201 imposes additional evidence requirements for private pensions. The original 2008 wording must be distinguished from the 2009 amendment. Alongside the pension certificate, the amended provision requires confirmation from a foreign pension administrator, trust, fund, insurer or bank that it administers funds for the pension-paying company or applicant; evidence of the existence and validity of the pension-paying and fund-administering entities; and a payment receipt or bank statement. The SNM checklist reflects this evidence chain. [P4], [P13]
The wording should not be presented as an express actuarial requirement to prove that all future lifetime payments are already fully capitalised. Additional solvency or funding evidence may be appropriate for unusual products, but that is evidence planning rather than a quotation of the statutory test.
“Private pension” or “annuity” is only a starting point. A guarantee period, lump-sum option, freely cancellable withdrawal plan, fixed payment term and genuine lifetime entitlement are different features. Missing information should be resolved through appropriate institutional confirmations, not assumptions.
Table 5 · Pension types and evidence of eligibility
| Benefit type | Classification / Preliminary assessment | Core evidence |
|---|---|---|
| State retirement pension | Generally close to the government-source category. | Institutional confirmation of entitlement, monthly amount, currency, current payment and lifetime duration. |
| Civil-service or public-sector pension | Generally close to the government-source category. | Award and current confirmation; explain suspension or reduction provisions. |
| Lifetime occupational pension | Generally a private source. | Pension confirmation plus evidence of fund administration, existence/validity and payment. |
| Private lifetime annuity / insurance pension | Potentially eligible; substantial documentation needed. | Contractual or institutional confirmation of lifetime duration and the complete Article 201 evidence chain. |
| Survivor pension | Individual assessment. | Own entitlement, source, amount, duration and possible termination conditions. |
| Disability or incapacity benefit | Individual assessment. | Document time limits, reviews, revocation conditions and duration expressly. |
| Fixed-term pension or withdrawal plan | Not inherently payable for life. | A long term is not the same as lifetime duration. |
| Portfolio withdrawals, rent, dividends or capital | Not clearly established as a pension by the statutory wording. | Relevant to other legal or financial-capacity questions only. |
| Future entitlement / pension forecast | Not yet a pension in payment. | Final entitlement and payment confirmation once the benefit starts. |
Table 6 · Quality checks for pension certificates
| Required information | Purpose | Typical supplementary evidence |
|---|---|---|
| Full name and identifying details | Connect the benefit to the applicant. | Award/policy number or date of birth. |
| Type and legal basis of the benefit | Identify the pension and its qualifying source. | Award, scheme rules or contract extract. |
| Monthly amount, currency and payment frequency | Check threshold and conversion. | Current payment notice or bank statement. |
| Express lifetime duration | Core Article 200 requirement. | Separate institutional confirmation. |
| Current payment status | Distinguish payment from a future entitlement. | Recent payment evidence. |
| Issuer, capacity, date and contact details | Verification and authentication. | Original or verifiable signature and official contact details. |
| Private pensions: fund administration and institutional status | Additional amended Article 201 requirements. | Fund administration for the company or applicant; existence/validity; payment evidence. |
Figure 3 · Eligibility and pension-evidence decision tree
3. Pension threshold, property and family
3.1 Standard amount and foreign currency
The pension must generally amount to at least B/.1,000 monthly or the foreign-currency equivalent. Record the original currency, monthly amount, payment frequency and a traceable conversion. A favourable historic exchange rate does not establish the value at filing. Where the margin is narrow, a documented buffer is prudent; it does not replace lifetime-entitlement evidence. [P3], [P4]
3.2 Property rule
Where the applicant has personally acquired property in Panama for more than B/.100,000, the minimum monthly pension may fall to B/.750. The wording requires ownership a título personal and an amount superior a B/.100,000. Exactly B/.100,000, a purchase option, corporate ownership or another asset must not be assumed equivalent. The checklist identifies a Registro Público certificate as evidence. [P3], [P4]
Property does not replace the pension; it changes the threshold only. It does not create automatic residence, tax treatment, bank acceptance or customs privileges.
3.3 Spouses and dependants
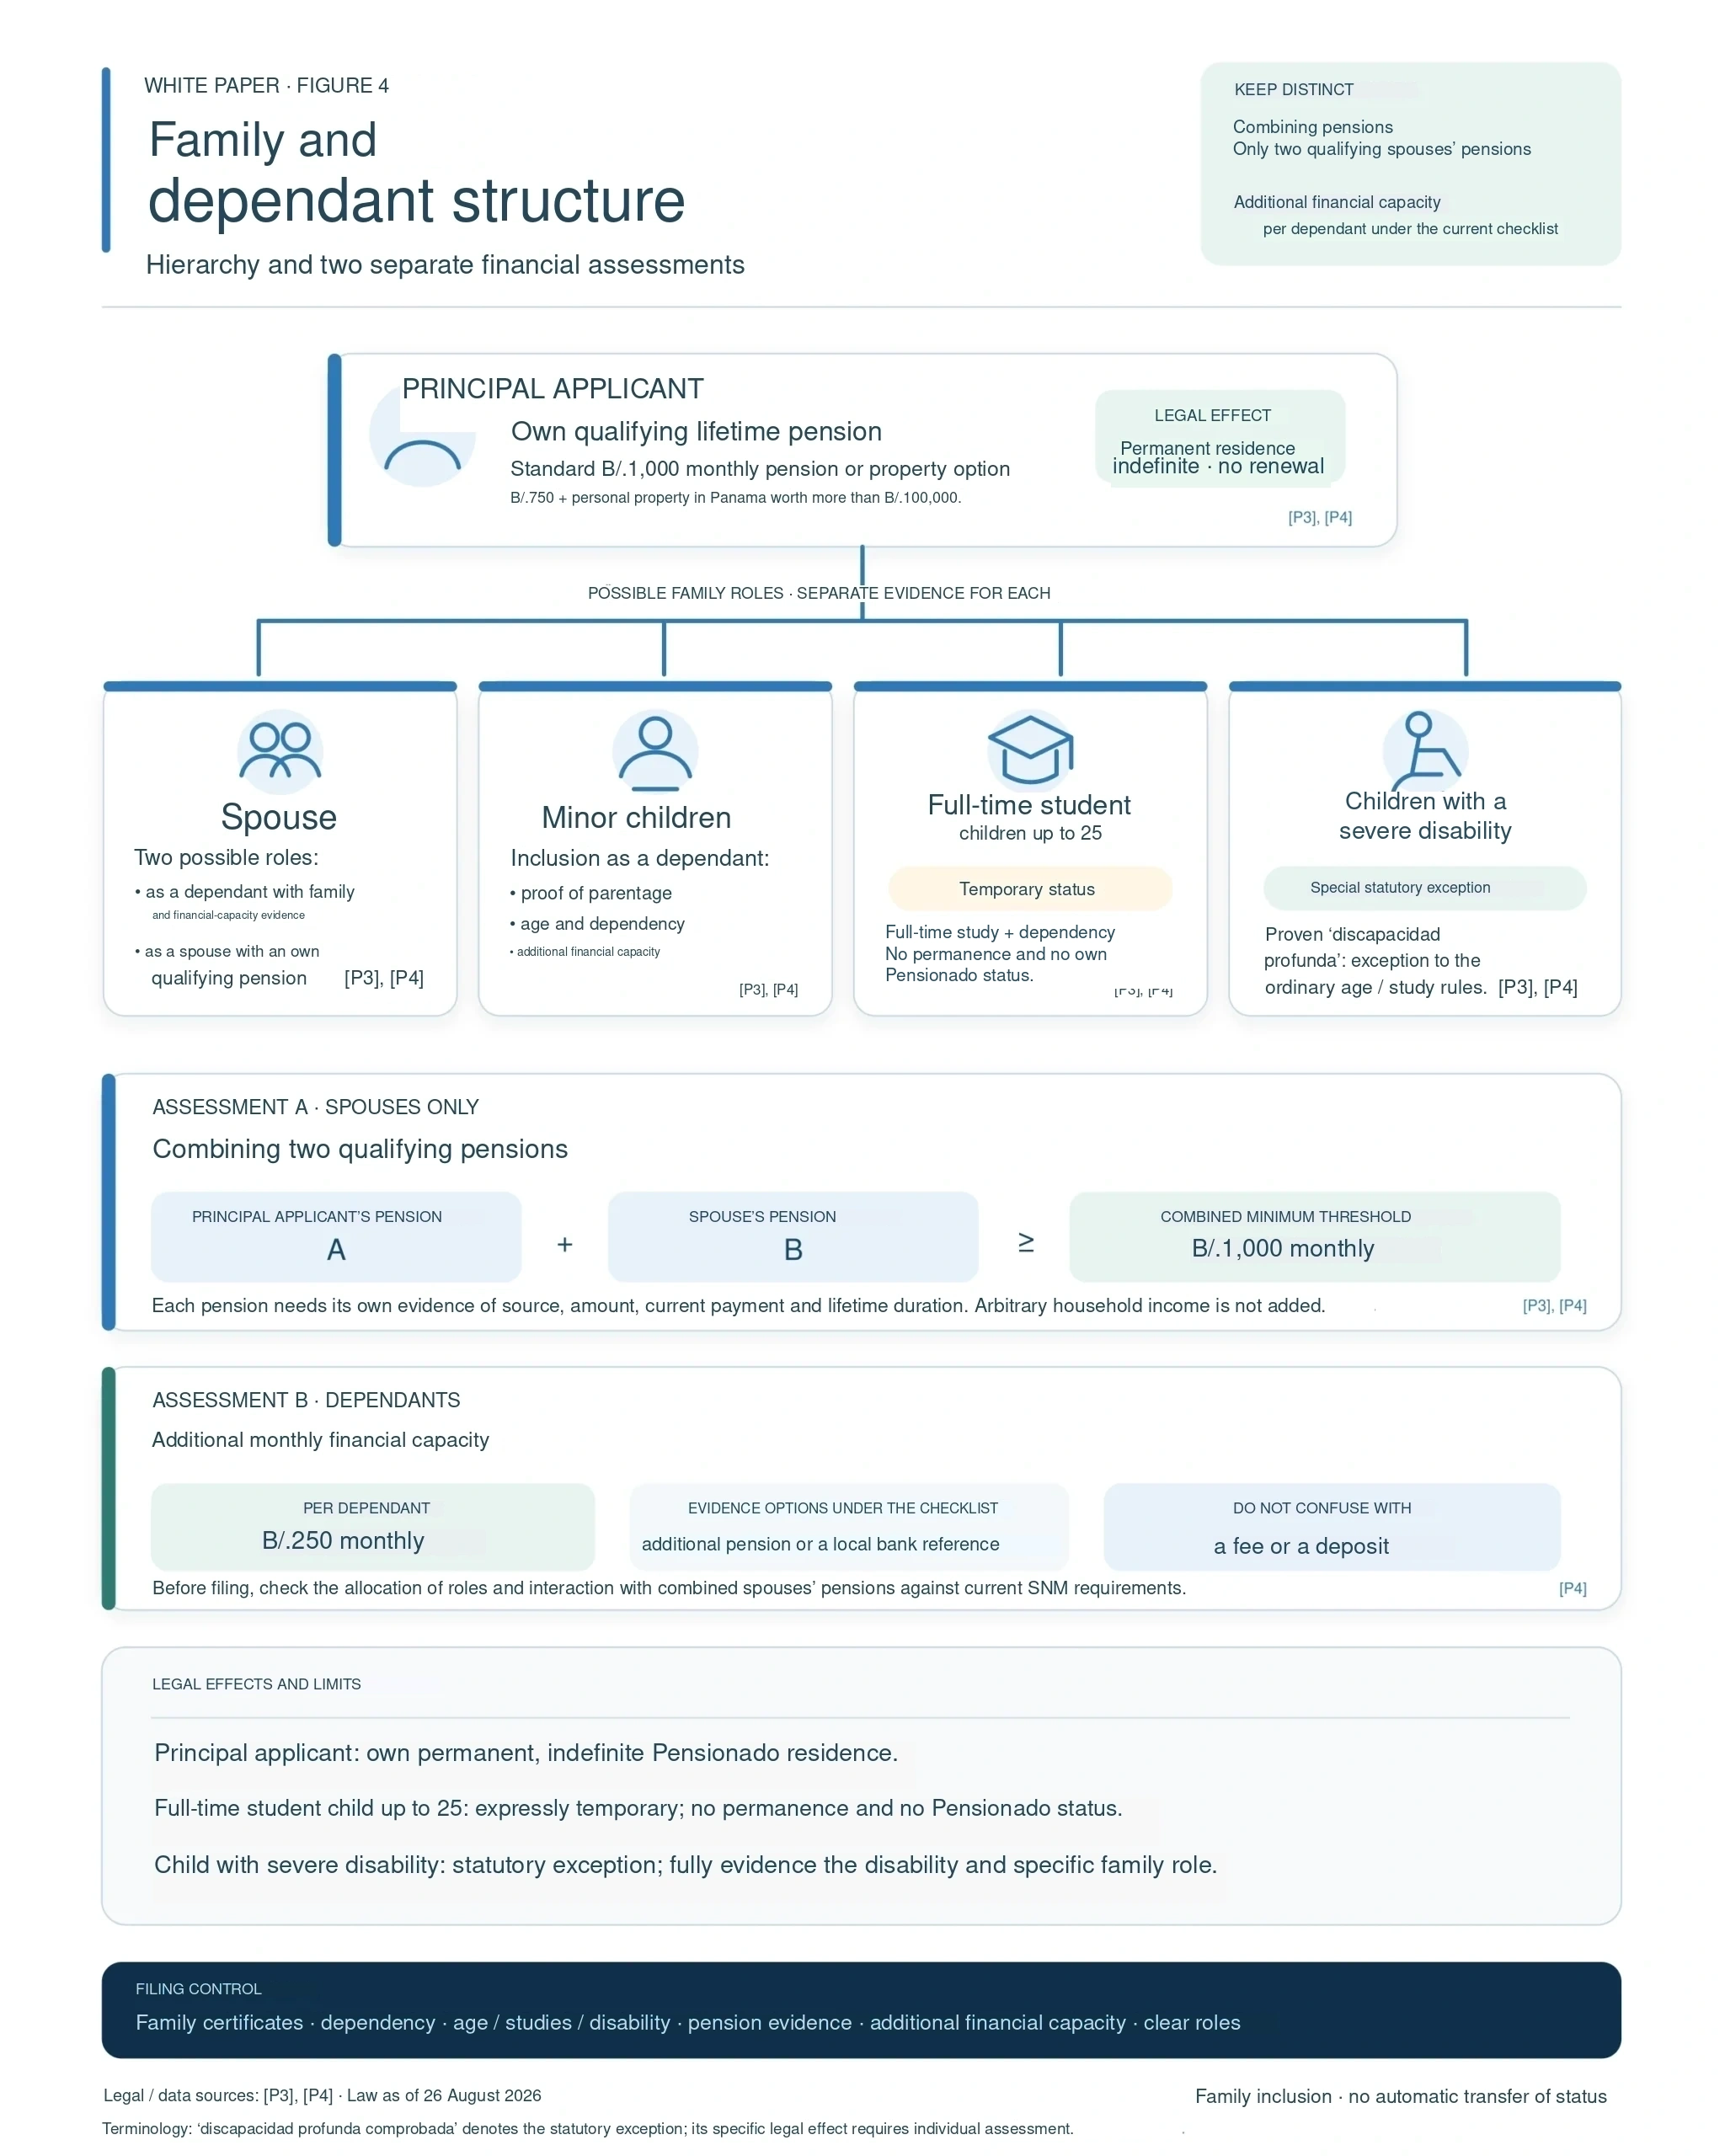
Article 201 permits spouses to meet the pension threshold using both qualifying pensions. Each benefit requires its own evidence of source, duration and authenticity. The rule does not authorise pooling arbitrary employment, rental or investment income. [P3]
The SNM checklist also requires additional monthly financial capacity of B/.250 per dependant, evidenced by additional pension or a local bank reference. This is neither a fee nor a deposit. The interaction between combined spouses’ pensions and dependant solvency must be checked against the actual family roles and current SNM requirements before filing. [P4]
3.4 Children
The special provision allows dependent children studying full time to receive temporary status up to age 25, with dependency evidence. This is not independent permanent Pensionado status. Article 202 contains an exception to the ordinary age/study rules for children with a documented severe disability. [P3], [P4]
Table 7 · Pension thresholds and family applications
| Situation | Pension / financial-capacity requirement | Consequence or assessment |
|---|---|---|
| One principal applicant | At least B/.1,000 lifetime pension. | Standard route. |
| Personal Panama property worth more than B/.100,000 | At least B/.750 lifetime pension plus ownership/acquisition evidence. | Only the pension threshold is reduced. |
| Spouses with two pensions | The two qualifying pensions may be combined. | Document each pension fully. |
| One dependant | B/.250 additional monthly financial capacity under the checklist. | Assess additional pension or local bank-reference evidence. |
| Two dependants | B/.500 additional monthly financial capacity as an arithmetic total. | Document each person and legal status. |
| Student child aged 18–24 | Family, dependency, full-time study and financial-capacity evidence. | Temporary status up to 25; no independent permanent residence. |
| Child with a severe disability | Individual family and medical evidence. | Special Article 202 assessment. |
Figure 4 · Family and dependant structure
4. International documents, apostilles and translation
4.1 Document planning by issuing country
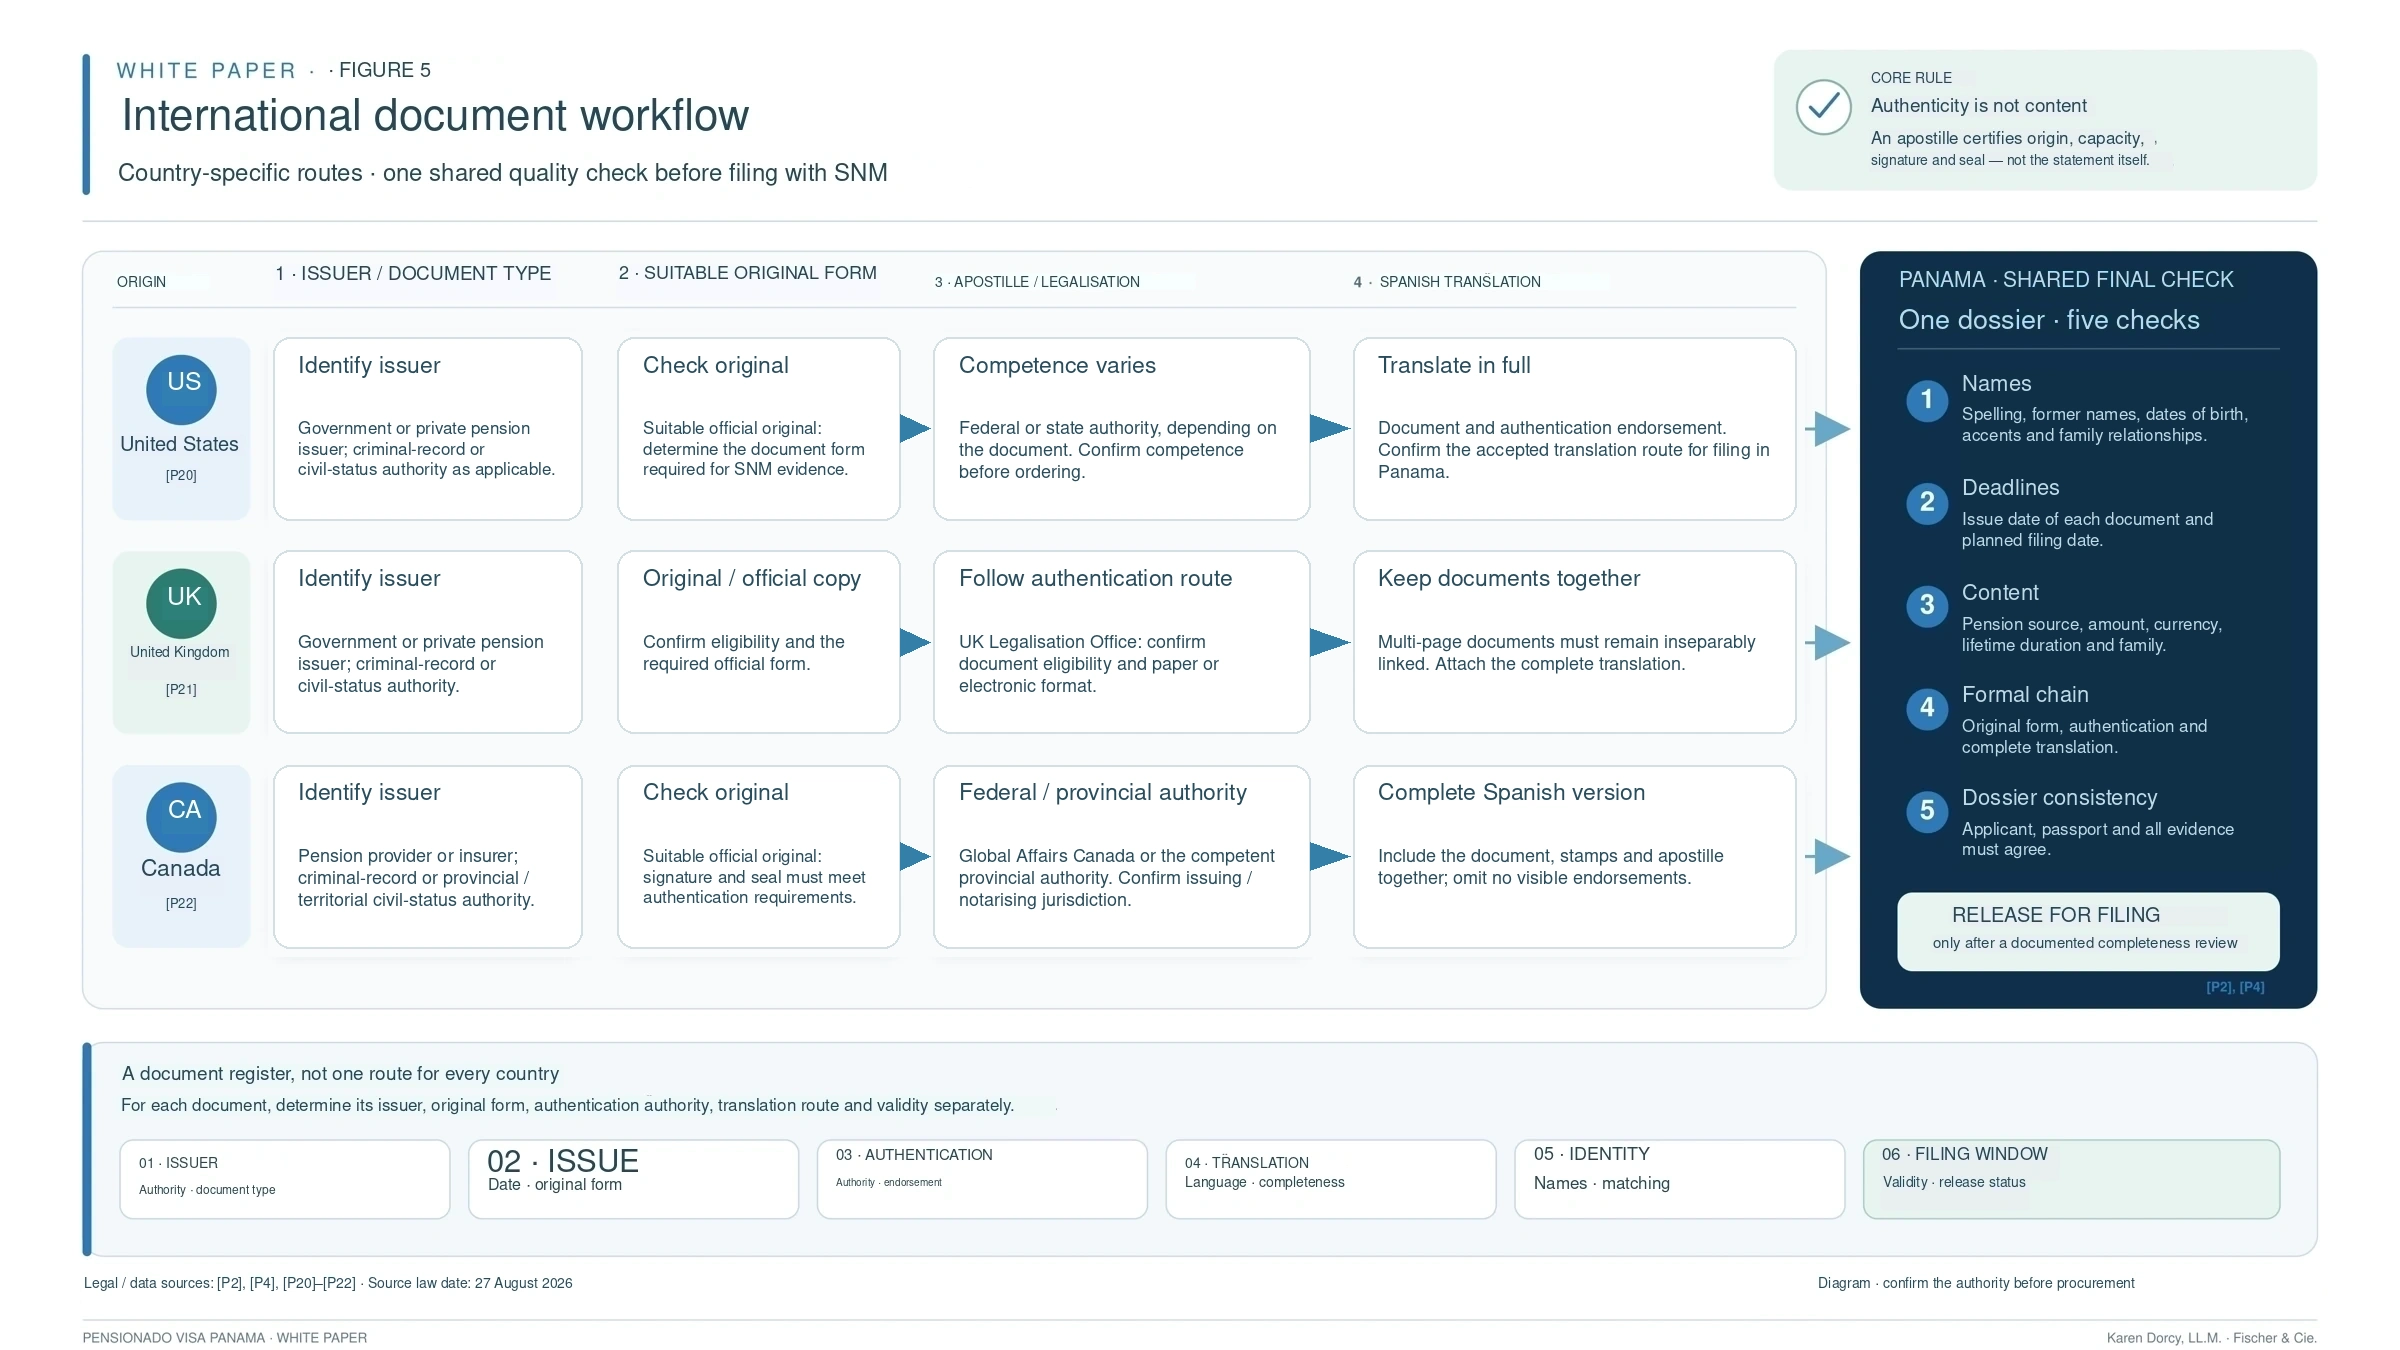
Pension certificates, criminal records and civil-status documents usually originate abroad. A single international checklist must not conceal national differences. For each document, identify the issuer, required original form, competent authentication authority, Spanish translation route and applicable currency requirements. The table illustrates US, UK and Canadian coordination; applicants from other countries require the same document-specific assessment. [P2], [P4], [P20]–[P22]
Table 8 · Document coordination: United States, United Kingdom and Canada
| Document | United States | United Kingdom | Canada | Final Panama review |
|---|---|---|---|---|
| Pension evidence | Government or private pension provider; identify the actual issuer. | Government or private pension provider; identify the actual issuer. | Government, occupational pension or insurer; identify the actual issuer. | Source, amount, currency and duration; additional private-pension evidence. |
| Criminal record | Determine the required criminal-record authority and document before ordering. | Determine the required police certificate and issuing authority before ordering. | Determine the required criminal-record document and issuing authority before ordering. | Relevant nationality/residence history, original form, currency, authentication and translation. |
| Marriage / birth certificate | Competent vital-records office. | Competent civil register. | Competent provincial or territorial vital-records office. | Relationship, names, date and suitable current official copy. |
| Apostille | Federal and state documents follow different apostille routes. [P20] | The UK Legalisation Office checks eligible UK documents; confirm paper or electronic form. [P21] | Global Affairs Canada or the competent provincial authority, depending on where the document was issued or notarised. [P22] | An apostille authenticates formal origin, not substantive content. |
| Translation | After confirming the final document and authentication chain. | The same sequence applies. | The same sequence applies. | The Spanish version must cover the original, apostille, stamps and annotations. |
4.2 Criminal record, health certificate and passport
Article 28 identifies passport copy, criminal record from the country of origin or residence, health certificate and personal declaration as general file components. The relevant country or countries must be determined from the applicant’s actual history. A blanket requirement covering every previous country of residence is not asserted. [P2], [P4]
The health certificate must be issued within three months before filing. Other documents require assessment against the checklist and individual file; a uniform validity period for all documents would be inaccurate. Passport details, names, dates of birth and former names must agree or be linked by official supporting records.
4.3 Authentication and translation
Table 9 · Apostille, translation and quality controls
| Stage | Function | Control question |
|---|---|---|
| Original / official copy | Establishes content in the form issued by the competent authority. | Is this particular copy suitable for use abroad? |
| Apostille or legalisation | Authenticates the signature, capacity and seal/stamp under the applicable procedure. | Which authority is competent for this document? |
| Spanish translation | Makes the content and authentication endorsements usable in the Panama file. | Does it fully match the final original, including its apostille? |
| Consistency check | Connects every document to the same person. | Have name variations, former names and transcription errors been resolved? |
| Deadline control | Checks that the documents remain usable on filing day. | Does the deadline derive from legislation, the checklist or an individual authority requirement? |
Figure 5 · International document workflow
5. Procedure and identity documents
5.1 Preliminary review and filing through an attorney
A sound process begins by reviewing the pension before incurring authentication, translation or travel costs. A document register then records issuer, date, original form, authentication route, translation and expiry controls. Application and power of attorney are submitted through an authorised apoderado legal. [P2], [P4]
Legal representation does not eliminate all personal participation. Lawful entry, identity checks, passport procedures, biometrics, card procedures and particular authority requirements may require attendance. Neither a single trip nor any fixed number of trips is promised.
5.2 Decision, rectification and remedies
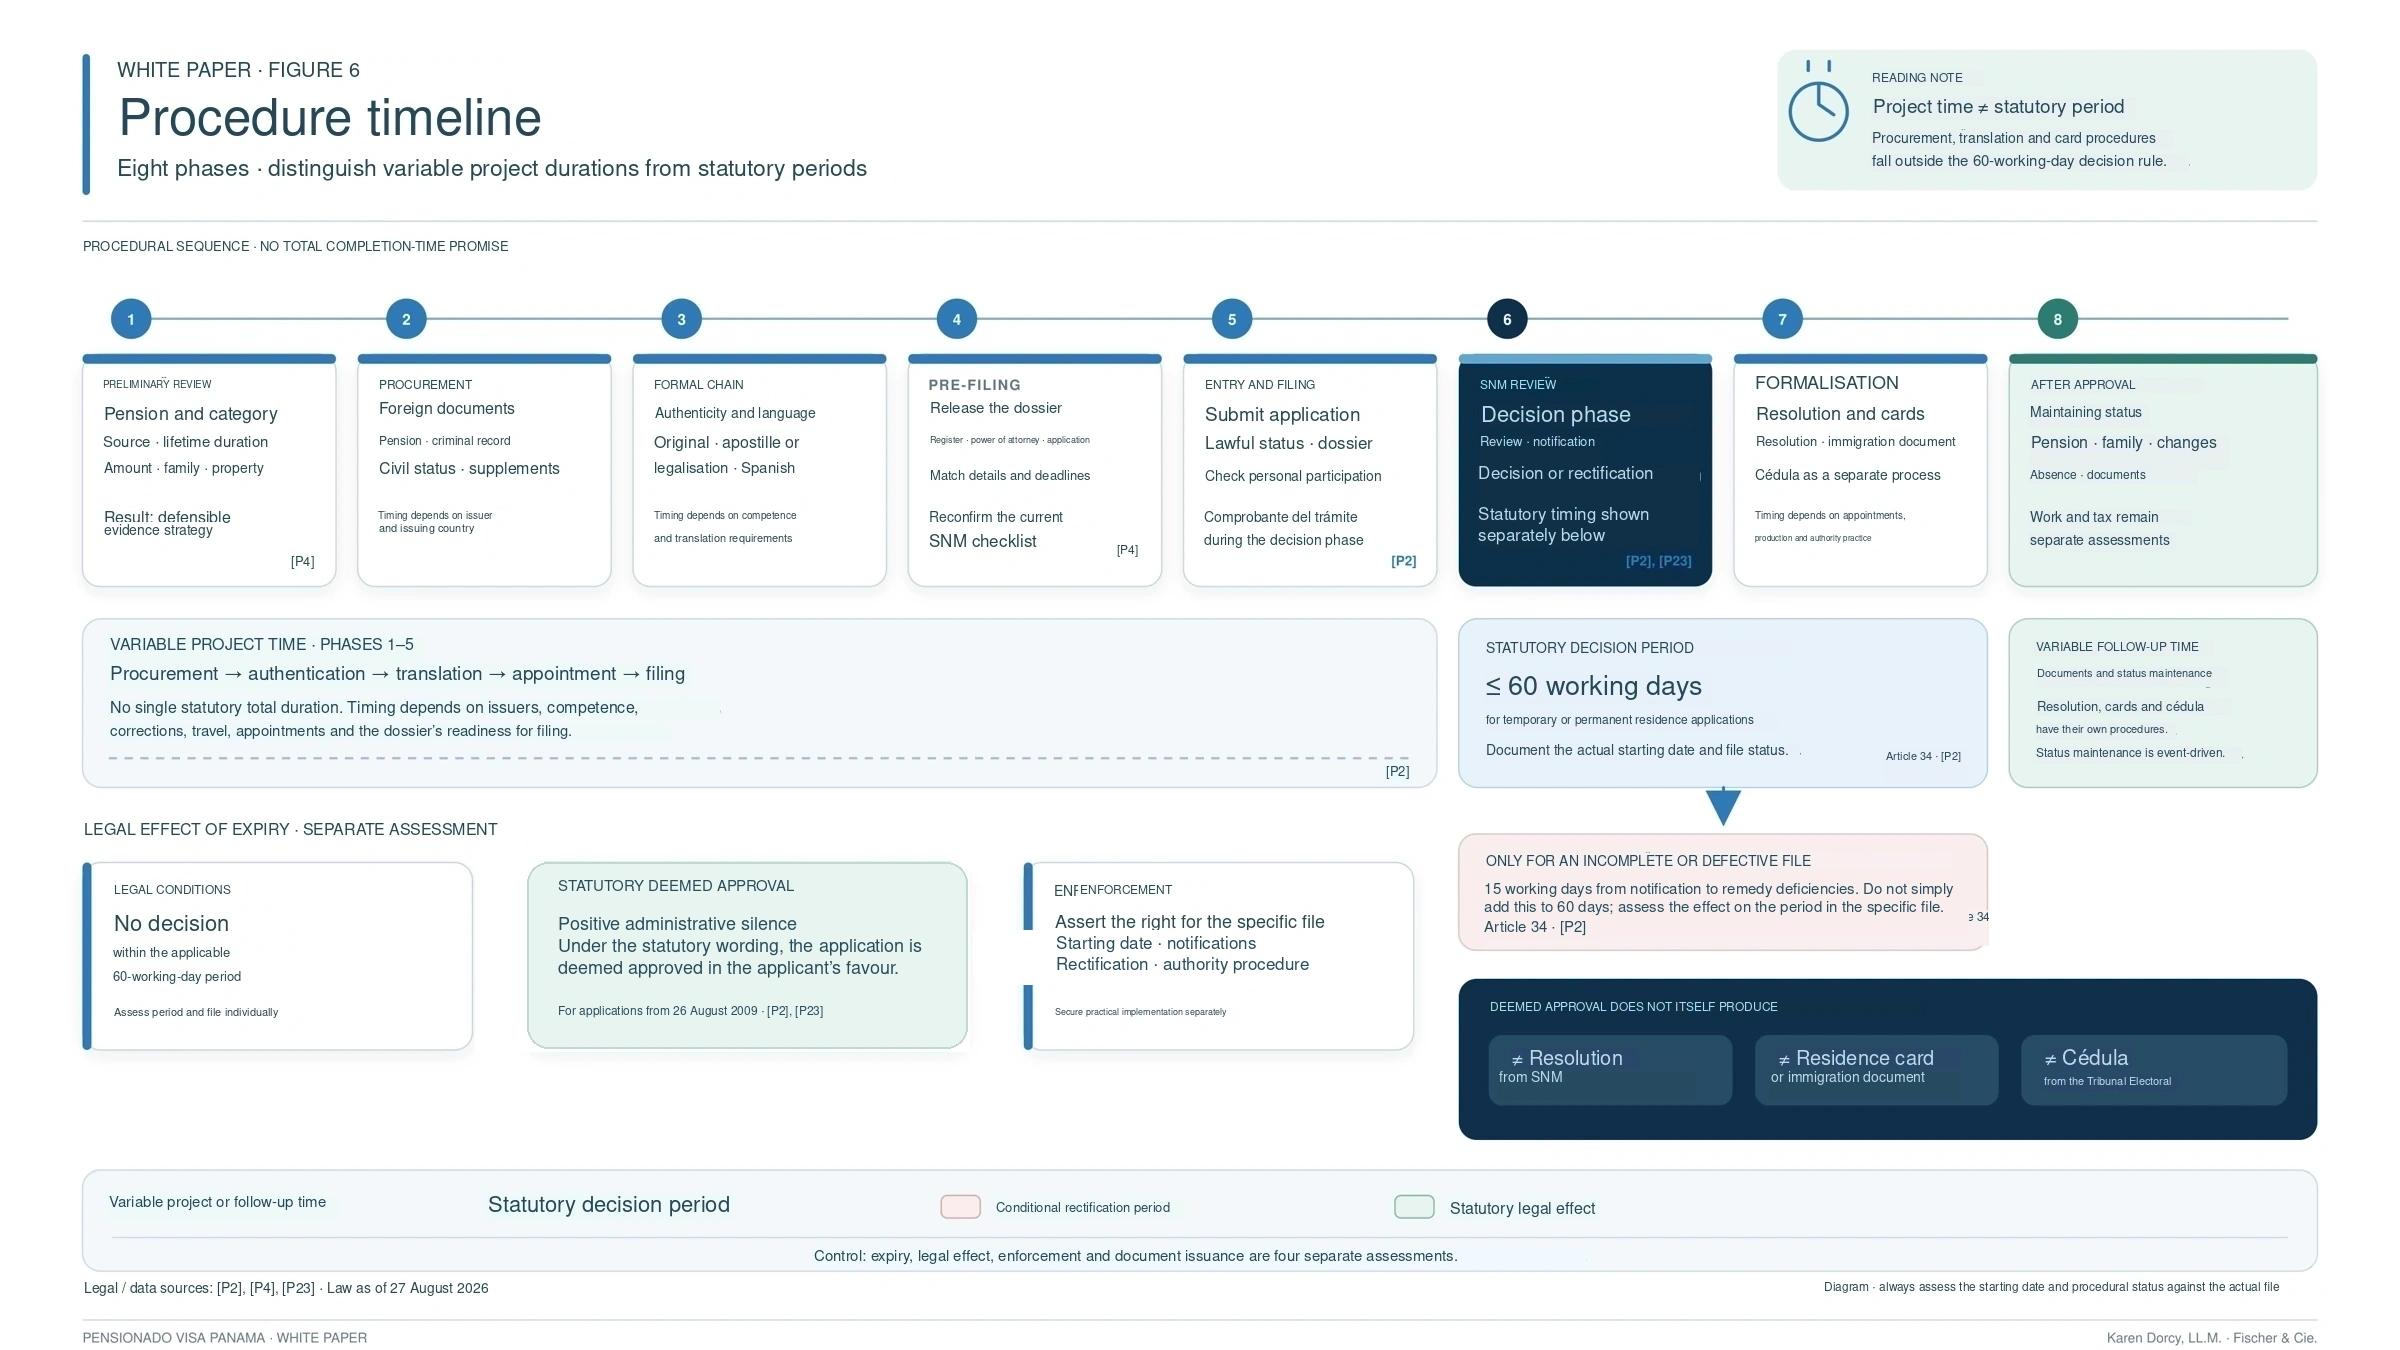
Article 34 generally specifies no more than 60 working days for temporary or permanent residence decisions and 15 working days after notification to remedy an incomplete or defective application. Procurement, authentication, translation, scheduling and card procedures are distinct from this decision phase. [P2]
Article 34’s transitional paragraph provides a deemed-approval mechanism where the decision period expires without a decision. The Procuraduría de la Administración addressed this positive administrative silence for temporary and permanent residence applications filed from 26 August 2009. Its application to a particular file requires legal assessment. [P2], [P23]
Distinguish legal effect from practical enforcement. Positive administrative silence does not allow an applicant to produce their own resolution, residence card or cédula without formalisation. The starting date, complete file, notifications, rectification requests and procedure for asserting the right require review. Deemed approval, its enforcement and subsequent document issuance are separate questions.
Following an adverse decision, preserve evidence of service and calculate the remedy deadline immediately. The Decreto Ley provides reconsideración and apelación within five working days. Informal correspondence does not replace a timely formal remedy. [P2]
5.3 Resolution, immigration document and cédula
The approval resolution, SNM immigration document and Tribunal Electoral identity document are separate steps. Filing, deemed approval or a provisional card do not themselves amount to a cédula. The Tribunal Electoral source cited here is general guidance on identity services, not a verified Pensionado-specific checklist. Requirements, appointments and charges must be confirmed for the subsequent procedure. [P2], [P11], [P23]
Table 10 · Procedure without completion-time promises
| Phase | Deliverable | Timing and attendance |
|---|---|---|
| 1 · Eligibility review | Assess source, lifetime duration, amount, family and property route. | Not an authority deadline; depends on evidence quality. |
| 2 · Overseas documents | Complete pension, criminal-record and civil-status evidence. | Depends on institutions and issuing countries. |
| 3 · Authentication / translation | Match final originals to their Spanish versions. | Separate from SNM processing time. |
| 4 · Pre-filing | Approve file register, power of attorney, application and cost plan. | Recheck the SNM checklist. |
| 5 · Entry and filing | Lawful status and complete filing. | Personal attendance depends on the case. |
| 6 · SNM review | Decision, targeted rectification or assessment of the consequences of expiry. | Up to 60 working days; 15 working days for rectification. Any Article 34 deemed-approval claim requires separate assessment. [P2], [P23] |
| 7 · Approval / documents | Resolution and separate card/identity procedures. | Deemed approval does not replace practical document issuance. |
| 8 · Maintaining status | Monitor changes, absence, pension, family, work and taxation. | Triggered by relevant events. |
Figure 6 · Procedure timeline
6. Costs and financial requirements
6.1 The Pensionado exception to Article 28(4)
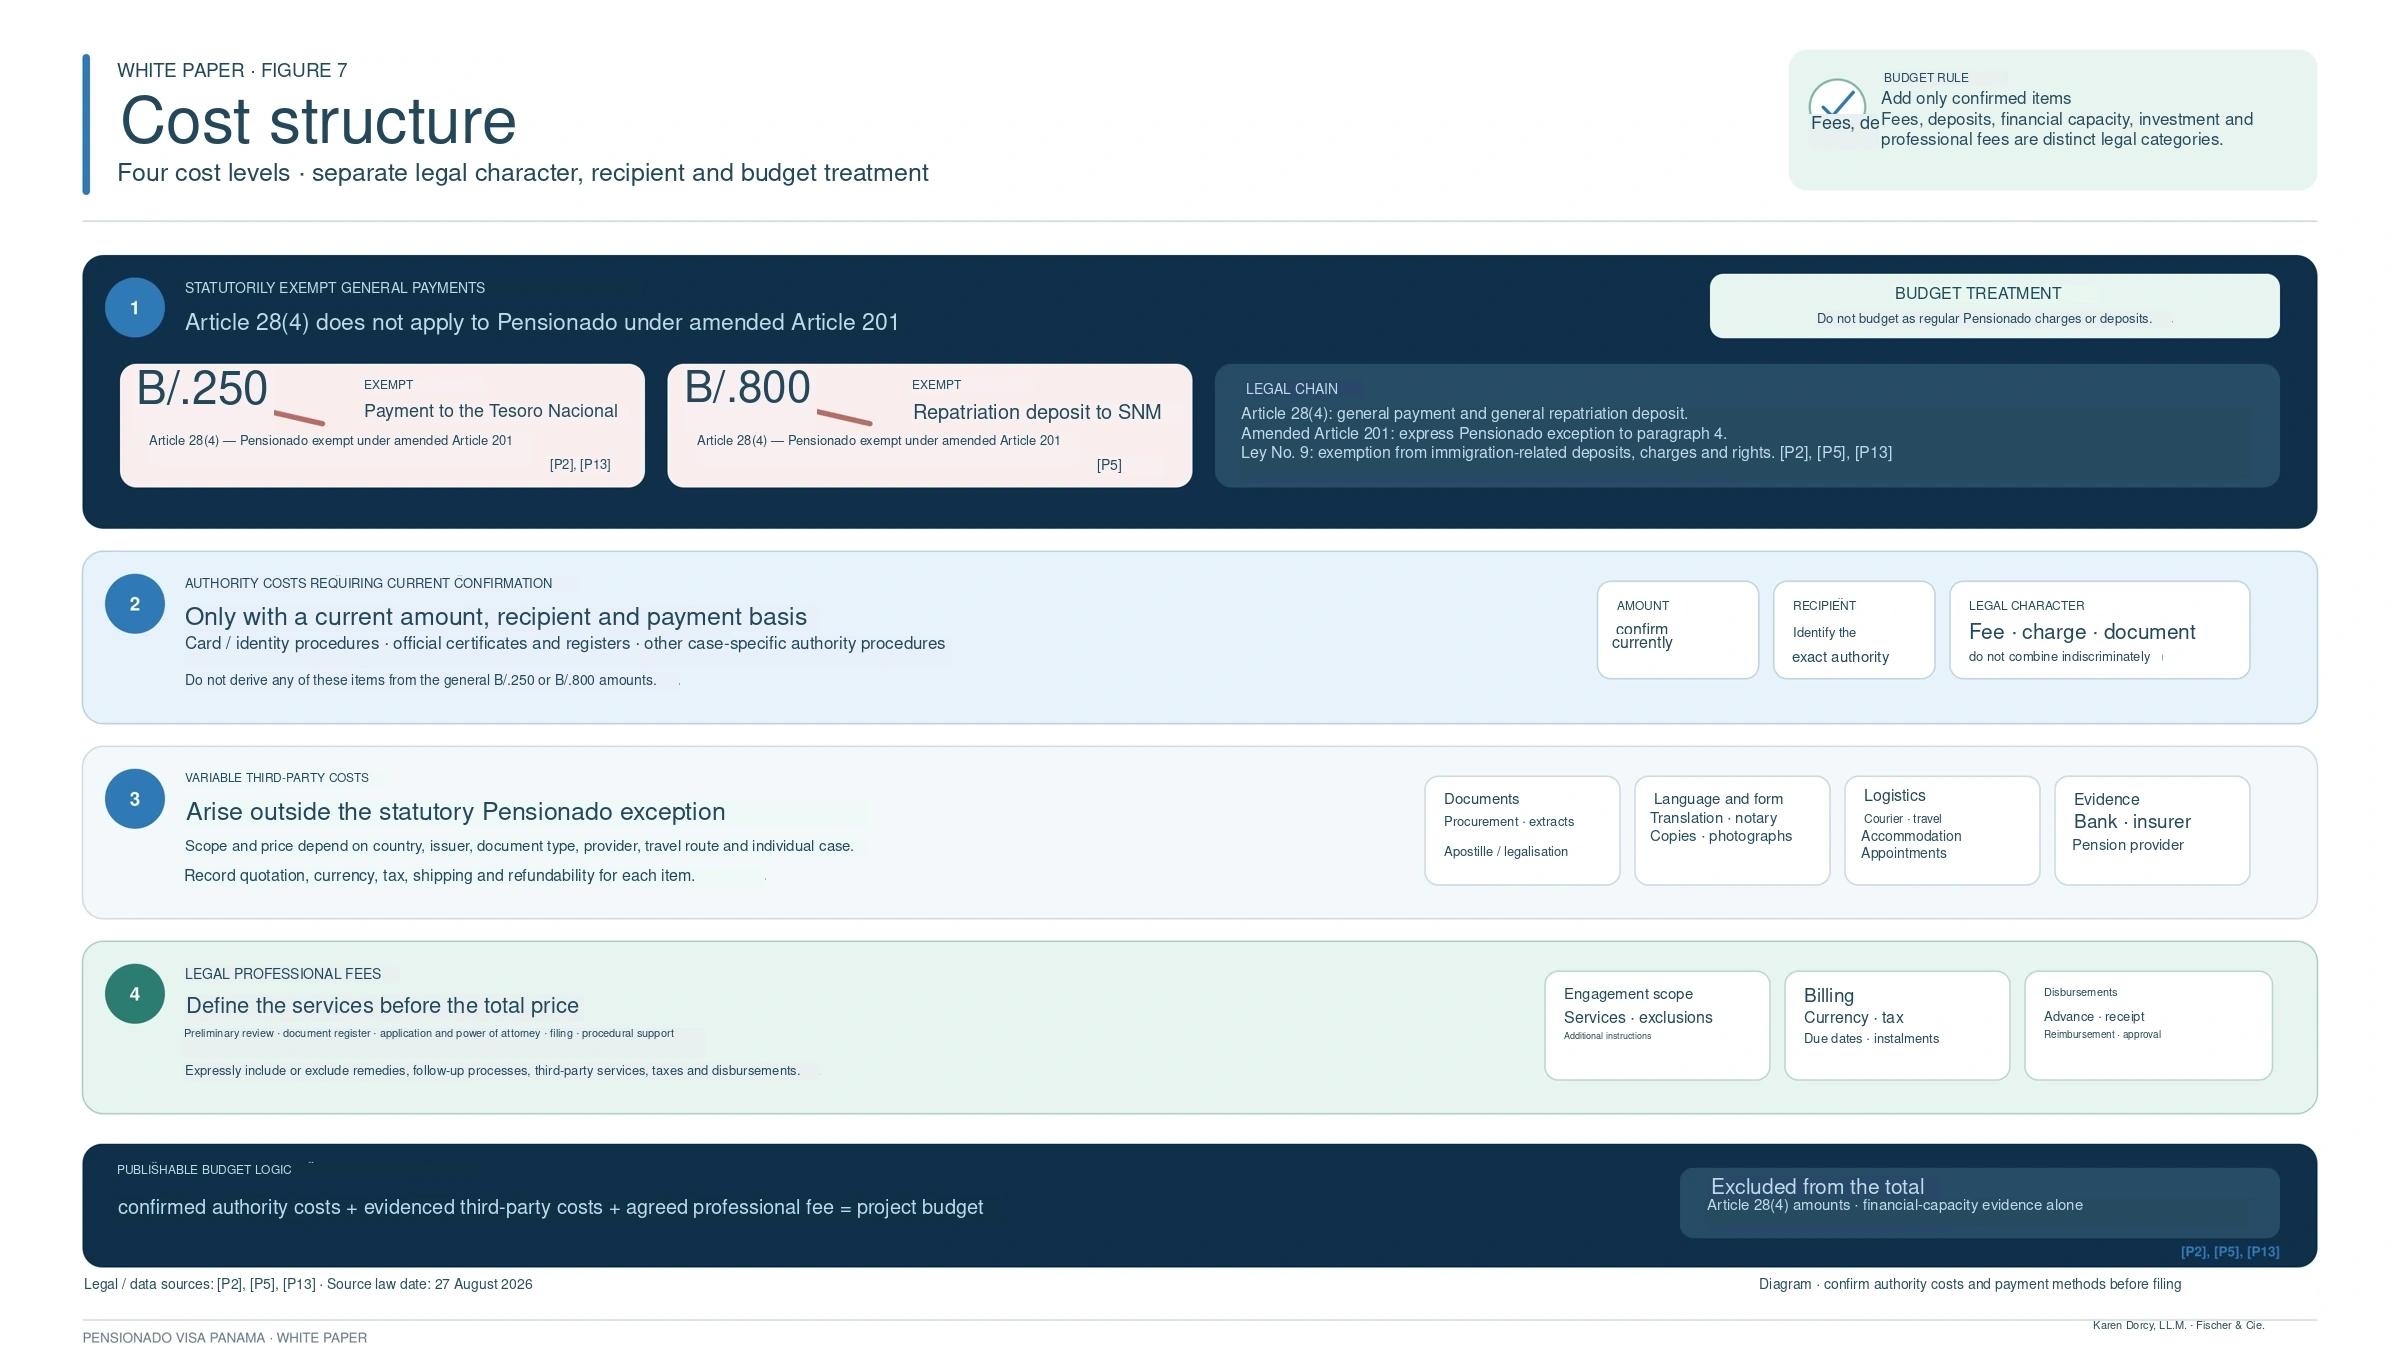
Article 28(4) of the general immigration framework specifies B/.250 for the Tesoro Nacional and B/.800 as a repatriation deposit. For jubilados and pensionados, the amended Article 201 is more specific: Decreto Ejecutivo No. 26/2009 requires the general Article 28 documents except item 4. Ley No. 9 also contains an immigration-related exemption. Neither general amount is therefore budgeted as a regular Pensionado charge. [P2], [P5], [P13]
As the regular Pensionado application does not include a fixed repatriation deposit, routine refund planning does not arise. If an authority requests a different payment in a particular case, obtain written confirmation of its legal basis, recipient, character and any refund entitlement before paying.
6.2 Variable expenses and professional fees
Documents, authentication, translations, notaries, registers, couriers, travel, accommodation, card/identity procedures and legal services remain separate items. A useful budget distinguishes government charges, deposits, financial-capacity evidence, third-party expenses and professional fees. It specifies currency, recipient, payment date and assumptions rather than an unsupported all-inclusive figure.
Table 11 · Charges, deposits, solvency, expenses and fees
| Cost category | Legal character | Amount / position | Budget treatment |
|---|---|---|---|
| General Article 28(4) Tesoro Nacional payment | General immigration payment. | B/.250; Pensionado exempt under amended Article 201. | Do not budget as a regular Pensionado charge. |
| General Article 28(4) repatriation deposit | Deposit under the general residence rules. | B/.800; Pensionado exempt under amended Article 201. | Do not budget as a regular Pensionado deposit. |
| Dependant financial capacity | Eligibility/evidence requirement, not a payment. | B/.250 monthly per dependant under the checklist. | Record as pension/bank evidence, not a fee. |
| Documents and authentication | Charge of the issuing or authenticating body. | Varies by country, document and authority. | Record evidence, currency and due date. |
| Translation, notary, register and courier | Third-party service / local formality. | Varies by scope and provider. | Separate service scope and disbursements. |
| Travel and accommodation | Personal project expenses. | Variable. | Not a government charge |
| Card and identity procedures | Separate administrative procedure. | Confirm immediately before the relevant step. | Do not reuse an outdated flat figure. |
| Professional fee | Contractual remuneration. | Depends on the engagement. | Separate fees, taxes, disbursements and third-party costs. |
Figure 7 · Cost categories
7. Maintaining residence, absence and cancellation
7.1 Permanent residence and its continuing basis
Indefinite residence does not remove continuing notification duties or the need to retain a lawful basis. Article 31 includes loss of the grounds for approval, incompatible activities and fraudulent or altered documents among cancellation grounds. Changes to the pension, provider or payment structure therefore require more than routine private administration. [P2]
The public checklist addresses filing, not a universal post-approval schedule of life or pension certificates. It establishes neither a general annual reporting duty nor that changes are irrelevant. A provider change, interruption, authority request or survivor case requires individual review of notification and evidence obligations.
7.2 Absence and changes of details
For permanent residents, Article 31 identifies absence for more than two years as a cancellation ground unless justified and authorised by the SNM. This is not an annual minimum-days requirement, but it does not support indefinite absence without consequences. [P2]
Article 87 requires notification of changes of address and information. The provision specifies B/.100 for a first infringement and potential further immigration consequences for repetition. Record changes promptly and confirm the applicable notification procedure. [P2]
7.3 Death of the principal applicant and survivor benefits
The principal applicant’s death does not automatically transfer the pension or residence basis. A surviving spouse’s dependent status, own survivor benefit, amount, duration and possible independent residence route require separate assessment. Divorce, loss of dependency and children reaching an age limit also require review.
Table 12 · Status events and response
| Event | Legal relevance | Immediate review |
|---|---|---|
| Address / personal-data change | Article 87 and current SNM procedure. | Formal notification, evidence and updated file copy. |
| Absence exceeding two years | Potential Article 31 cancellation ground. | Assess duration, justification and authorisation before the threshold is exceeded. |
| Pension changes or ends | Potential loss of the basis for approval. | Document the new source, amount, duration and transition. |
| Death of the principal applicant | Change in the family and pension basis. | Assess own survivor benefit and residence route. |
| Separation / divorce / dependency ends | Change in family circumstances. | Clarify own status and notification obligations. |
| Starting an activity | Potential incompatibility / work-permit issue. | Review Ley No. 9, MITRADEL, professional rules and tax before starting. |
| Adverse decision | Reconsideración / apelación: generally five working days. | Immediately secure service details, deadline, file and available remedy. |
8. Employment, self-employment and company roles
8.1 Two layers of rules
Ley No. 9 contains a general restriction on work for its Pensionado beneficiaries and specified exceptions concerning certain specialised services for the state, qualifying investment activity subject to prior MITRADEL authorisation, and membership of governing bodies of companies in which the person has invested. The precise conditions must be reviewed before relying on an exception. [P5]
Decreto Ejecutivo MITRADEL No. 6/2023 and MITRADEL’s classification set out specific work-permit categories. Permanent residence alone must not be treated as a generic work authorisation. The available categories depend on particular residence, family, quota, special-law, investment or protection circumstances. A proposed activity must be assessed against Ley No. 9, the actual working arrangement and a genuinely applicable MITRADEL route. [P5], [P9], [P24]
8.2 Examine the activity, not its label
Calling work “remote”, “consulting”, a “board appointment” or “passive” does not decide its legality. Record actual tasks, place of performance, employer or client, subordination, remuneration, shareholding, professional regulation and connection to Panama. Restricted professions and employment quotas require separate analysis.
Table 13 · Employment, self-employment, company roles and remote work
| Activity | Starting position | Confirm before starting |
|---|---|---|
| Employment in Panama | Residence does not replace a work permit. | MITRADEL category, contract, quotas and restricted professions. |
| Self-employed services | Not authorised merely by Pensionado status. | Activity, dependency, RUC / aviso de operación and applicable permit route. |
| Company shareholding | Investment must be distinguished from work. | Passive holding, office, operational tasks and remuneration. |
| Director / board role | Ley No. 9 contains a specific exception linked to the person’s investment. | Role, investment, remuneration and actual operational responsibilities. |
| Specialised services to the state | Narrow statutory exception under Ley No. 9. | Availability of Panamanian professionals, engagement and necessary authorisations. |
| Remote work for foreign clients | No automatic Pensionado exception. | Place of performance, contract, subordination, professional rules and income source. |
| Managing personal assets | May fall outside an employment relationship. | Actual activities, consideration, corporate and tax issues. |
9. Tax residence, income source, banking and transfers
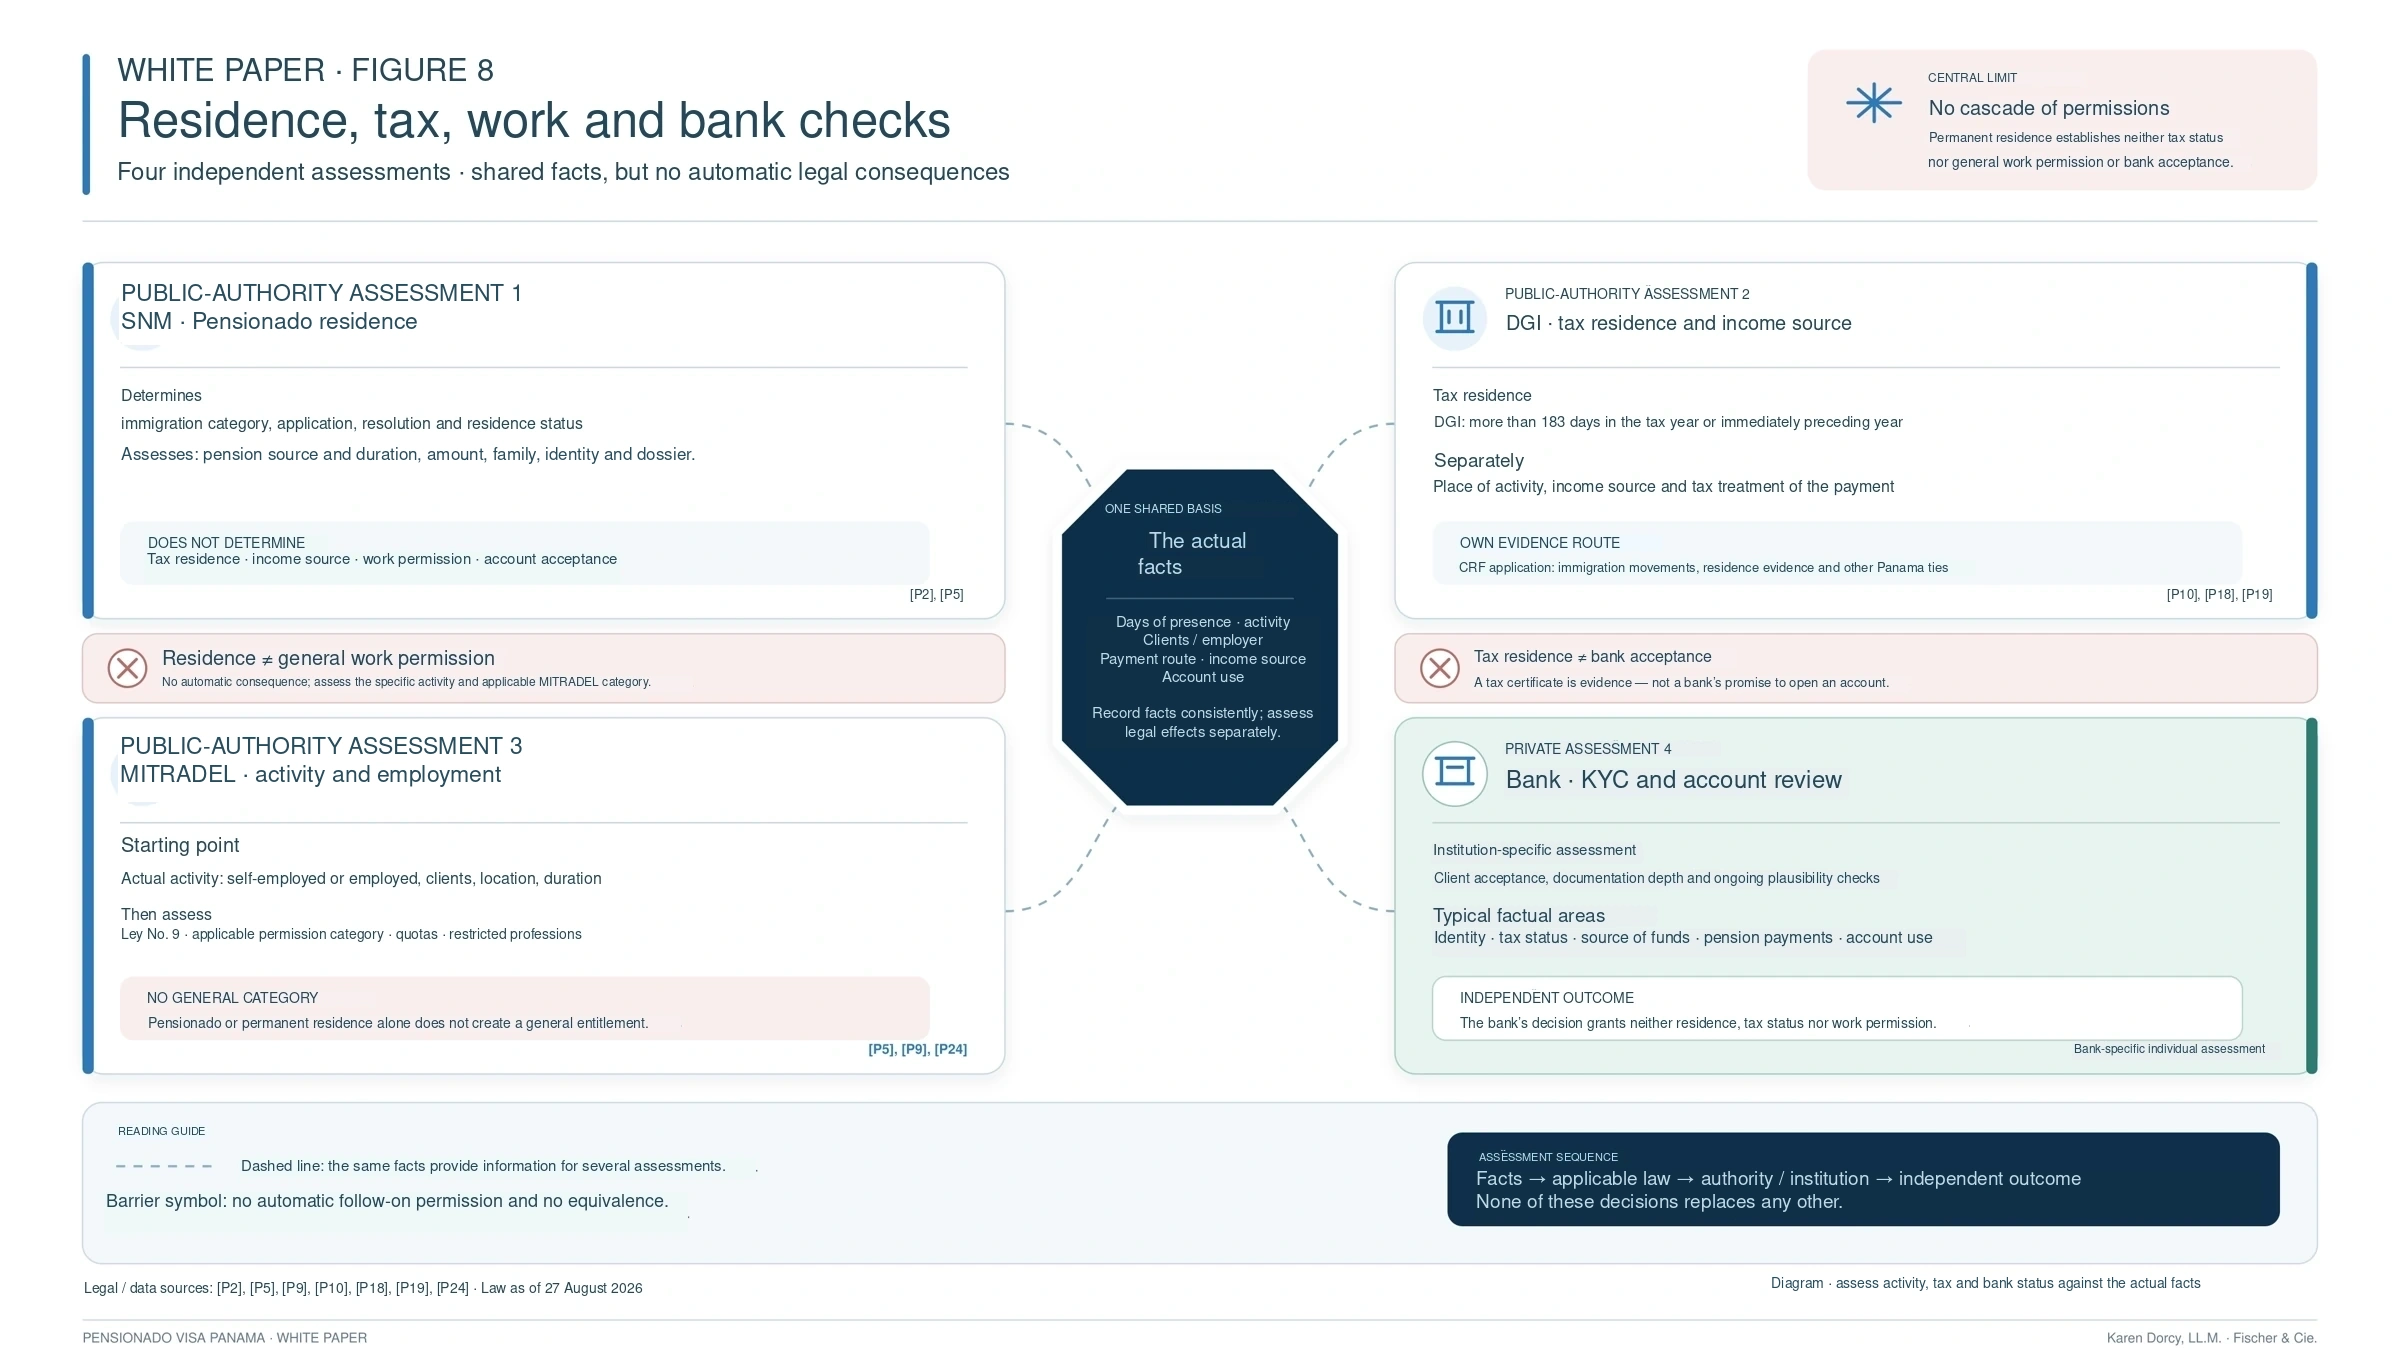
9.1 Immigration status does not determine taxation
The SNM grants Pensionado residence. Tax residence and income source follow tax law and DGI procedures. DGI guidance refers, among other criteria, to presence exceeding 183 days in the same tax year or the immediately preceding year. A tax-residence certificate requires supporting evidence of the relevant connections. This is not a complete statement of every applicable residence test. [P18], [P19]
The territorial principle is the starting point, not the conclusion. Each receipt must be classified under Article 694 and other applicable rules. For services, the actual place and nature of the activity may matter more than the client’s address or receiving account. Foreign receipts must not therefore be described as invariably tax-free. [P10]
For source methodology, [P10] is used for the basic Article 694 text introduced by Ley No. 6/2005 and its express source criteria. A particular tax opinion requires the applicable amendment chain, special rules, DGI practice and any treaty provisions to be reviewed separately. This commentary is not an individual tax opinion.
9.2 Foreign law remains outside the engagement
Whether an applicant remains tax-resident elsewhere, and the consequences for pensions, withholding, exit taxation, reporting, social security and treaties, must be assessed by qualified advisers in those jurisdictions. A Panamanian tax-residence certificate does not automatically settle those questions.
9.3 Banking, KYC, currency and source of funds
Residence approval does not oblige a bank to accept a customer. Banks assess identity, tax residences, source of funds, pension provider, account purpose, beneficial ownership and transaction profile. The immigration pension file may assist that assessment but does not replace it.
Keep the pension certificate, payment evidence and currency conversion consistent. Large transfers, property purchases and vehicle imports may require additional source-of-funds evidence. Neither account opening, processing time nor acceptance of a transfer is guaranteed.
Table 14 · Separate immigration, tax, work and banking assessments
| Area | Key question | Responsible body | Does not automatically establish |
|---|---|---|---|
| Pensionado residence | Does the applicant satisfy Articles 200–203? | SNM | Tax residence, exemption or work authorisation. |
| Tax residence | Are the applicable tax-residence criteria met? | DGI | Whether every foreign receipt is taxable or exempt. |
| Tax-residence certificate | Are the relevant factual connections sufficiently evidenced? | DGI | Issue merely on the strength of a residence card. |
| Income source | What is the source of this particular income under the Código Fiscal? | DGI / qualified adviser | Determination solely by a foreign client or overseas account. |
| Work permit | Is the specific activity lawful and authorised? | MITRADEL | Replacement of the permit by residence or tax registration. |
| Foreign-law consequences | What obligations remain in the relevant foreign jurisdiction? | Locally qualified advisers / authorities | Determination by this Panama commentary. |
| Bank acceptance | Does the applicant meet the bank’s KYC / AML requirements? | The particular bank | An entitlement arising from residence. |
Figure 8 · Immigration status, tax residence and work permission
10. Import privileges and statutory concessions
10.1 Imports under Ley No. 9
Ley No. 9 provides a one-time customs-tariff exemption for household and personal effects up to B/.10,000 and a vehicle privilege on a two-year cycle for personal or family use. It also restricts disposal: sale, rental, pledge or judicial disposal before the statutory conditions are met can trigger payment of duties and charges. Article 3 addresses the three-year rule for disposal of household goods. [P5]
A franquicia arancelaria is not automatic clearance. Before purchase or shipment, confirm beneficiary status, goods or vehicle, ownership, value, classification, timing, shipping documents, exemption procedure and remaining charges with Aduanas. Its general services portal is not a substitute for a complete, current Pensionado-specific filing checklist. The legal entitlement [P5] and operational procedure [P12] must therefore be distinguished.
Table 15 · Customs and immigration privileges under Ley No. 9
| Subject | Statutory privilege | Limits and procedure |
|---|---|---|
| Household / personal effects | One-time customs-tariff exemption. | Up to B/.10,000; personal / household use; confirm customs procedure before shipment. |
| Motor vehicle | Customs-tariff privilege for one vehicle. | Personal / family use; statutory two-year cycle; confirm vehicle and procedure requirements. |
| Disposal of exempt goods | Early disposal may trigger recovery of duties. | Clear sale, rental, pledge or disposal with Aduanas first. |
| Household goods after three years | Specific rule for later sale. | Record the exemption date. |
| Immigration-related payments | Exemption connected with obtaining Pensionado status. | Not a blanket exemption from every subsequent charge. |
| Special passport under Article 2(4) | Not a Pensionado entitlement under Article 1. | Historical rentista retirado benefit; do not market it as a Pensionado benefit. |
10.2 Who falls within Ley No. 6
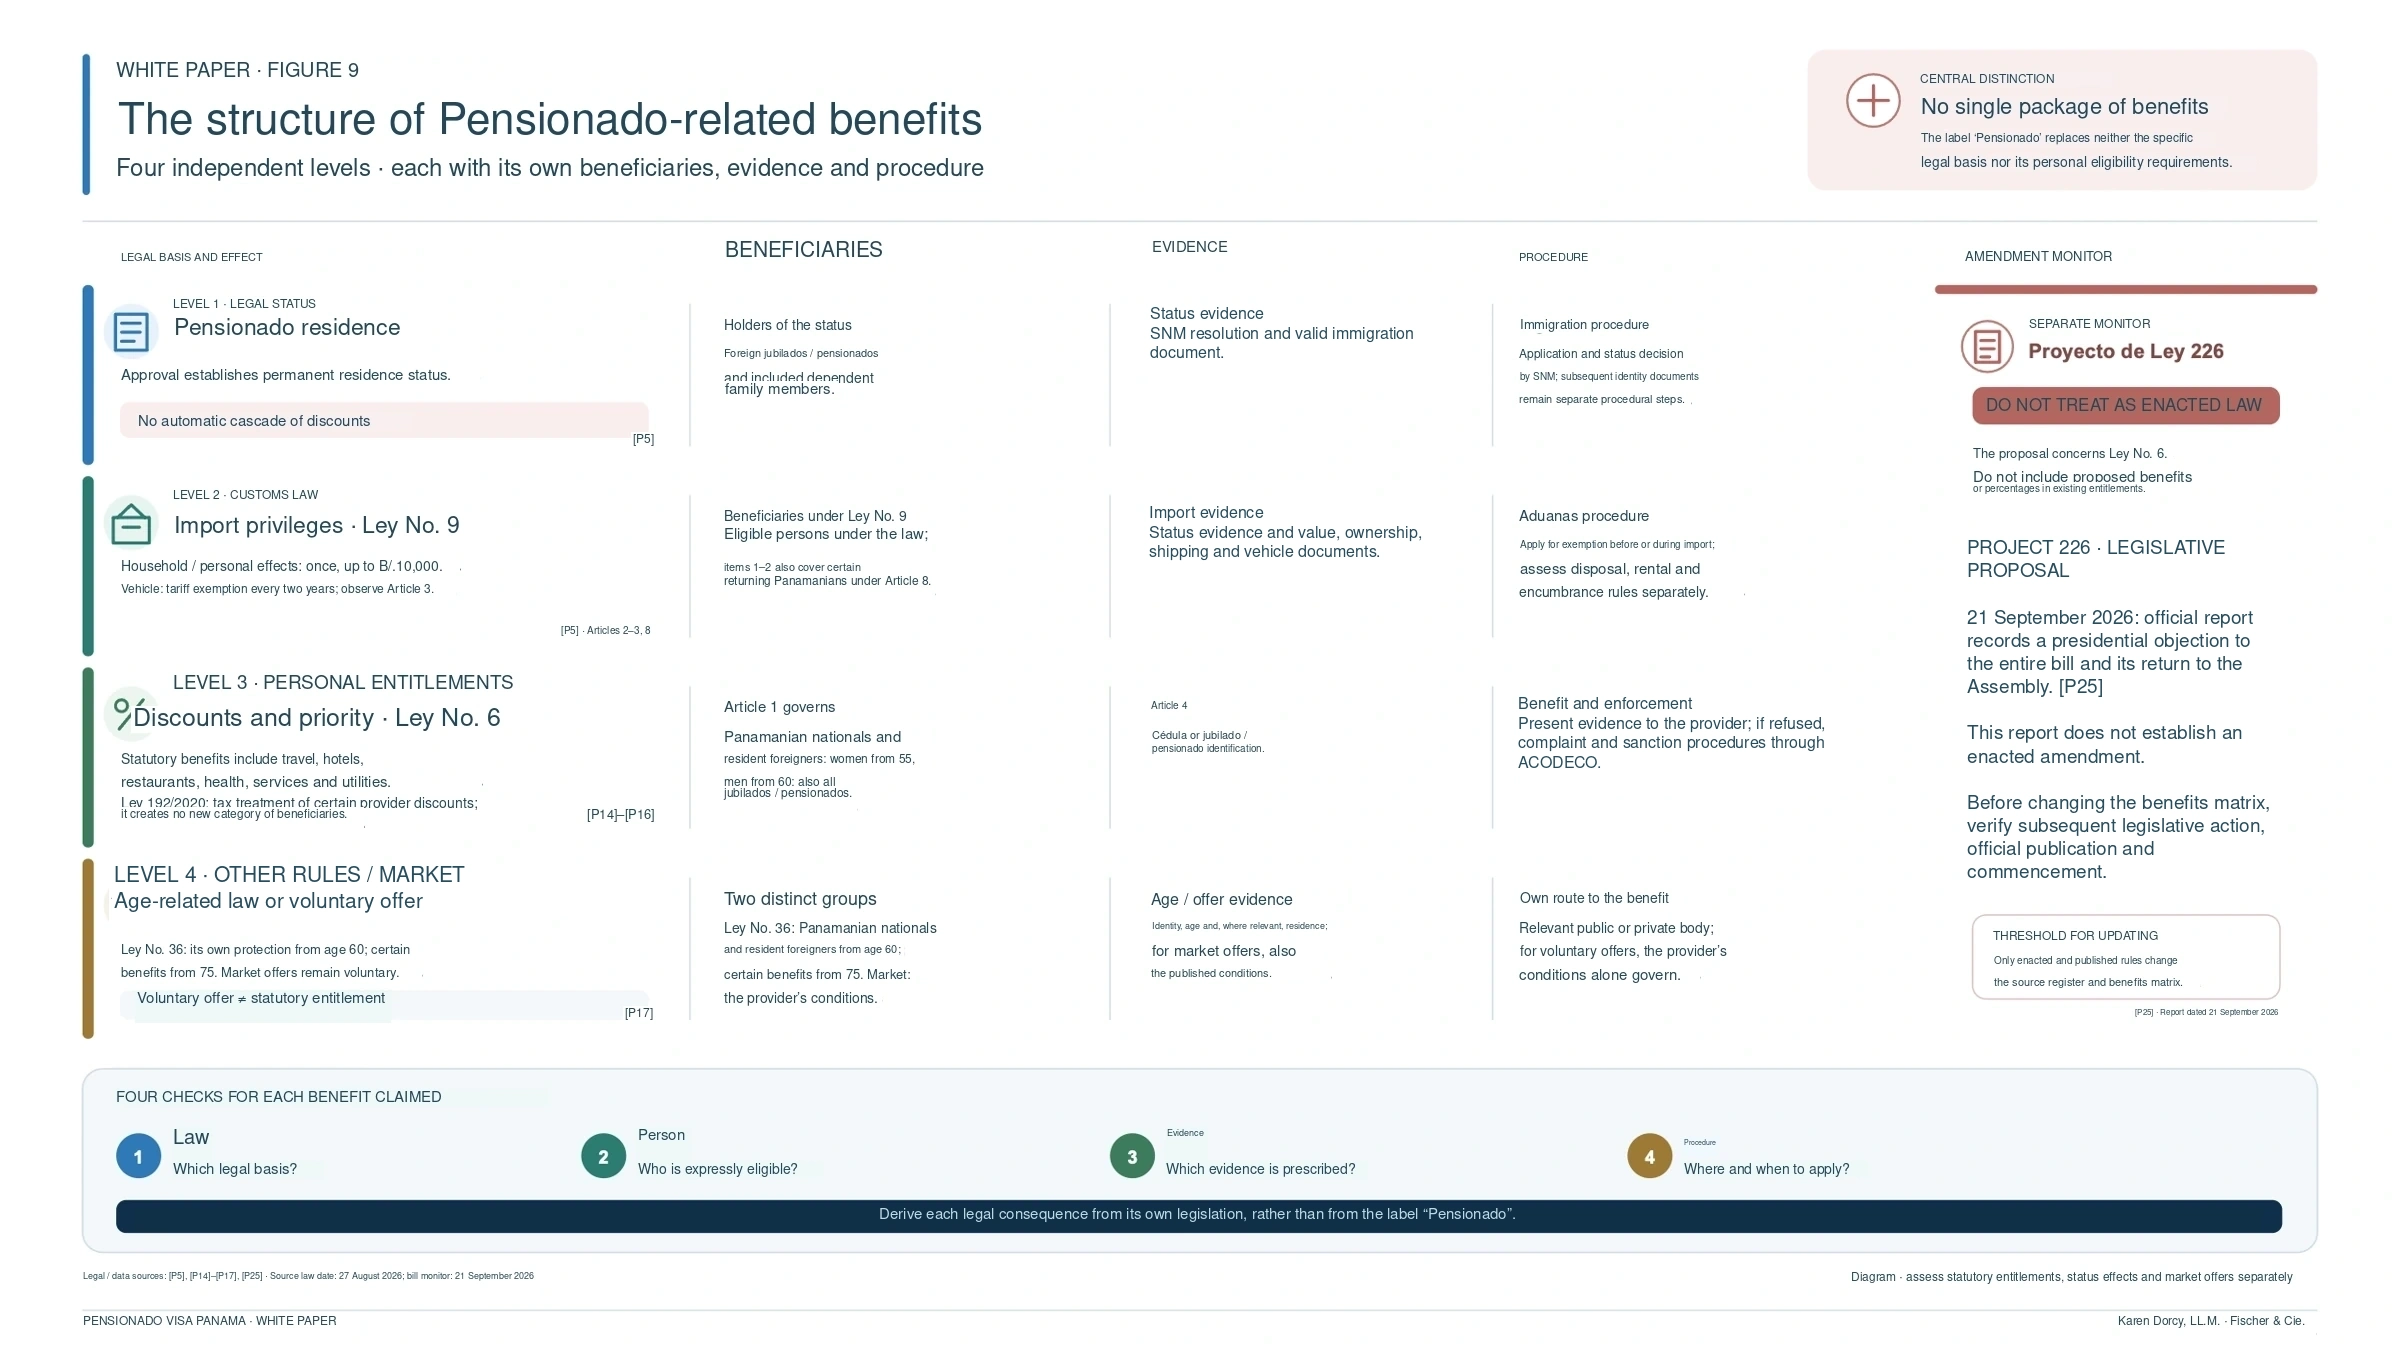
Ley No. 6 is a separate consumer-protection and social-benefit law. Its consolidated source text covers Panamanian or foreign residents meeting the stated age criteria—women aged at least 55 and men at least 60—and jubilados and pensionados of various categories. Entitlement follows the law’s personal scope and evidence requirements, not simply the label “Pensionado visa”. Benefits are non-transferable. [P14]
Article 4 addresses identity and pension-status evidence. Foreign beneficiaries should confirm which documents establish entitlement for the particular transaction. ACODECO handles enforcement. The tables below reproduce the baseline described in the German source edition; they are not confirmation of current rates or an assurance that a particular supplier or invoice qualifies. Check the applicable consolidated law and amendments before relying on a percentage. [P14], [P15]
Table 16 · Source-edition baseline: travel, food, health and services
| Service | Concession described in the source edition | Material limitation |
|---|---|---|
| Public entertainment: cinema, theatre, sport and similar | 50% of admission. | Certain charitable events excluded. |
| Intercity buses, trains and boats / ships | 30% of the fare. | The particular public-transport service. |
| Air tickets | 25 %. | Distinguish the fare from airport taxes and charges. |
| Hotels, motels and guesthouses | At least 50% Monday–Thursday; 30% Friday–Sunday. | Regular price and day of the week. |
| Restaurants | 25% of the eligible person’s meal. | Certain fondas excluded; not a household-wide discount. |
| Franchised fast-food outlets | 15 %. | The statutory type of establishment. |
| Private hospitals / clinics | 15% of the service bill. | Check individual invoice items. |
| Medicines | 20 %. | Particular dispensing transaction and proof of entitlement. |
| General / specialist medical and surgical professional fees | 20 %. | The professional fee, not automatically all third-party items. |
| Dental services / optometry | 15% each. | The particular service. |
| Technical and professional fees | 20 %. | Separate materials, taxes and third-party expenses. |
| Prostheses and assistive devices / accessories | 20 %. | Check the product category. |
| Health insurance | Adjustment intended to pass the benefit through premiums. | No fixed percentage promise without reviewing the policy. |
Table 17 · Source-edition baseline: finance, utilities and other matters
| Service | Concession described in the source edition | Material limitation |
|---|---|---|
| Loan arrangement costs / commission | 50% for personal and business loans. | Loan in the eligible person’s name. |
| FECI surcharge | Exemption. | The particular loan transaction. |
| Maximum permitted loan interest | 15% reduction from the legally permitted maximum rate. | Not a reduction of principal. |
| Owner-occupied home mortgage | One percentage-point interest reduction. | Own residential use; statutory preferential mortgages excluded. |
| Property tax | Freezing of the assessment described in the source. | Home in the person’s name and sole property. |
| Betterment levy | Exemption. | Sole property and own home; check transfer provisions. |
| Electricity | 25% up to 600 kWh monthly consumption. | Normal rate for excess consumption. |
| Landline telephone | 25% of the fixed connection charge. | Account in the person’s name, residential line, one telephone. |
| Water | 25% of the consumption tariff. | Consumption not exceeding B/.30; account in the person’s name; residential use. |
| Airport tax / charge | 50 %. | Separate from the ticket-fare concession. |
| Passport | 50% of passport price. | Foreign pensioners must not assume this applies to their foreign passport. |
| Funeral | 20% of coffin / urn and funeral services. | Deceased must fall within the statutory beneficiary group. |
| Priority service | Priority in public and private service offices. | No waiver of substantive requirements. |
| Qualifying associations | Special provisions for association property and registration fees. | Concerns organisations, not individual private invoices. |
10.3 No automatic all-purpose benefits card
Table 18 · Applying and evidencing concessions
| Question | Answer supported by the source framework | Practical consequence |
|---|---|---|
| Does PRP-JP alone activate every concession? | No; Ley No. 6 has its own scope and evidence rules. | Confirm entitlement and identification before the transaction. |
| Can a spouse use the other spouse’s entitlement? | No; Article 7 makes benefits non-transferable. | The spouse needs an independent basis of entitlement. |
| Does a concession cover every invoice item? | No; individual provisions define the service, consumption, account, ownership or use conditions. | Review invoice components separately. |
| What about people aged 75 or above? | Ley No. 36/2016 contains additional age-related provisions. | Do not confuse age-based legislation with Pensionado immigration status. [P17] |
| Are private senior tariffs statutory benefits? | Only where a relevant legal basis applies. | Identify voluntary commercial offers as such. |
10.4 Monitoring amendments to Ley No. 6
The government broadcaster SERTV reported on 21 September 2026 that Proyecto de Ley No. 226 had been vetoed in its entirety and returned to the National Assembly. The proposed expanded benefits must therefore not be presented as enacted rights on the basis of that bill. The tables identify the statutory baseline and its limitations; eligibility and the applicable rules must be checked for the particular transaction. [P25]
Publication and case review. Before a new edition or a transaction relying on a specific concession, check the Gaceta Oficial, the legislative record and all relevant amendments. A proposal, debate or veto is not by itself a consolidated statement of the law in force.
Figure 9 · Separate legal bases for Pensionado-related benefits
11. Naturalisation and nationality
Permanent Pensionado residence is not Panamanian citizenship and does not create automatic naturalisation. Article 10 of the Constitution establishes separate requirements and routes, including a general five-consecutive-year residence basis alongside language, civic and procedural requirements. Any later application must be assessed under the constitutional, statutory and administrative rules then applicable. [P1]
Retention, renunciation or loss of a foreign nationality, and related reporting or tax consequences, are outside the Panamanian engagement. Obtain qualified advice in the relevant country before taking a naturalisation step.
12. Risk matrix and fact check
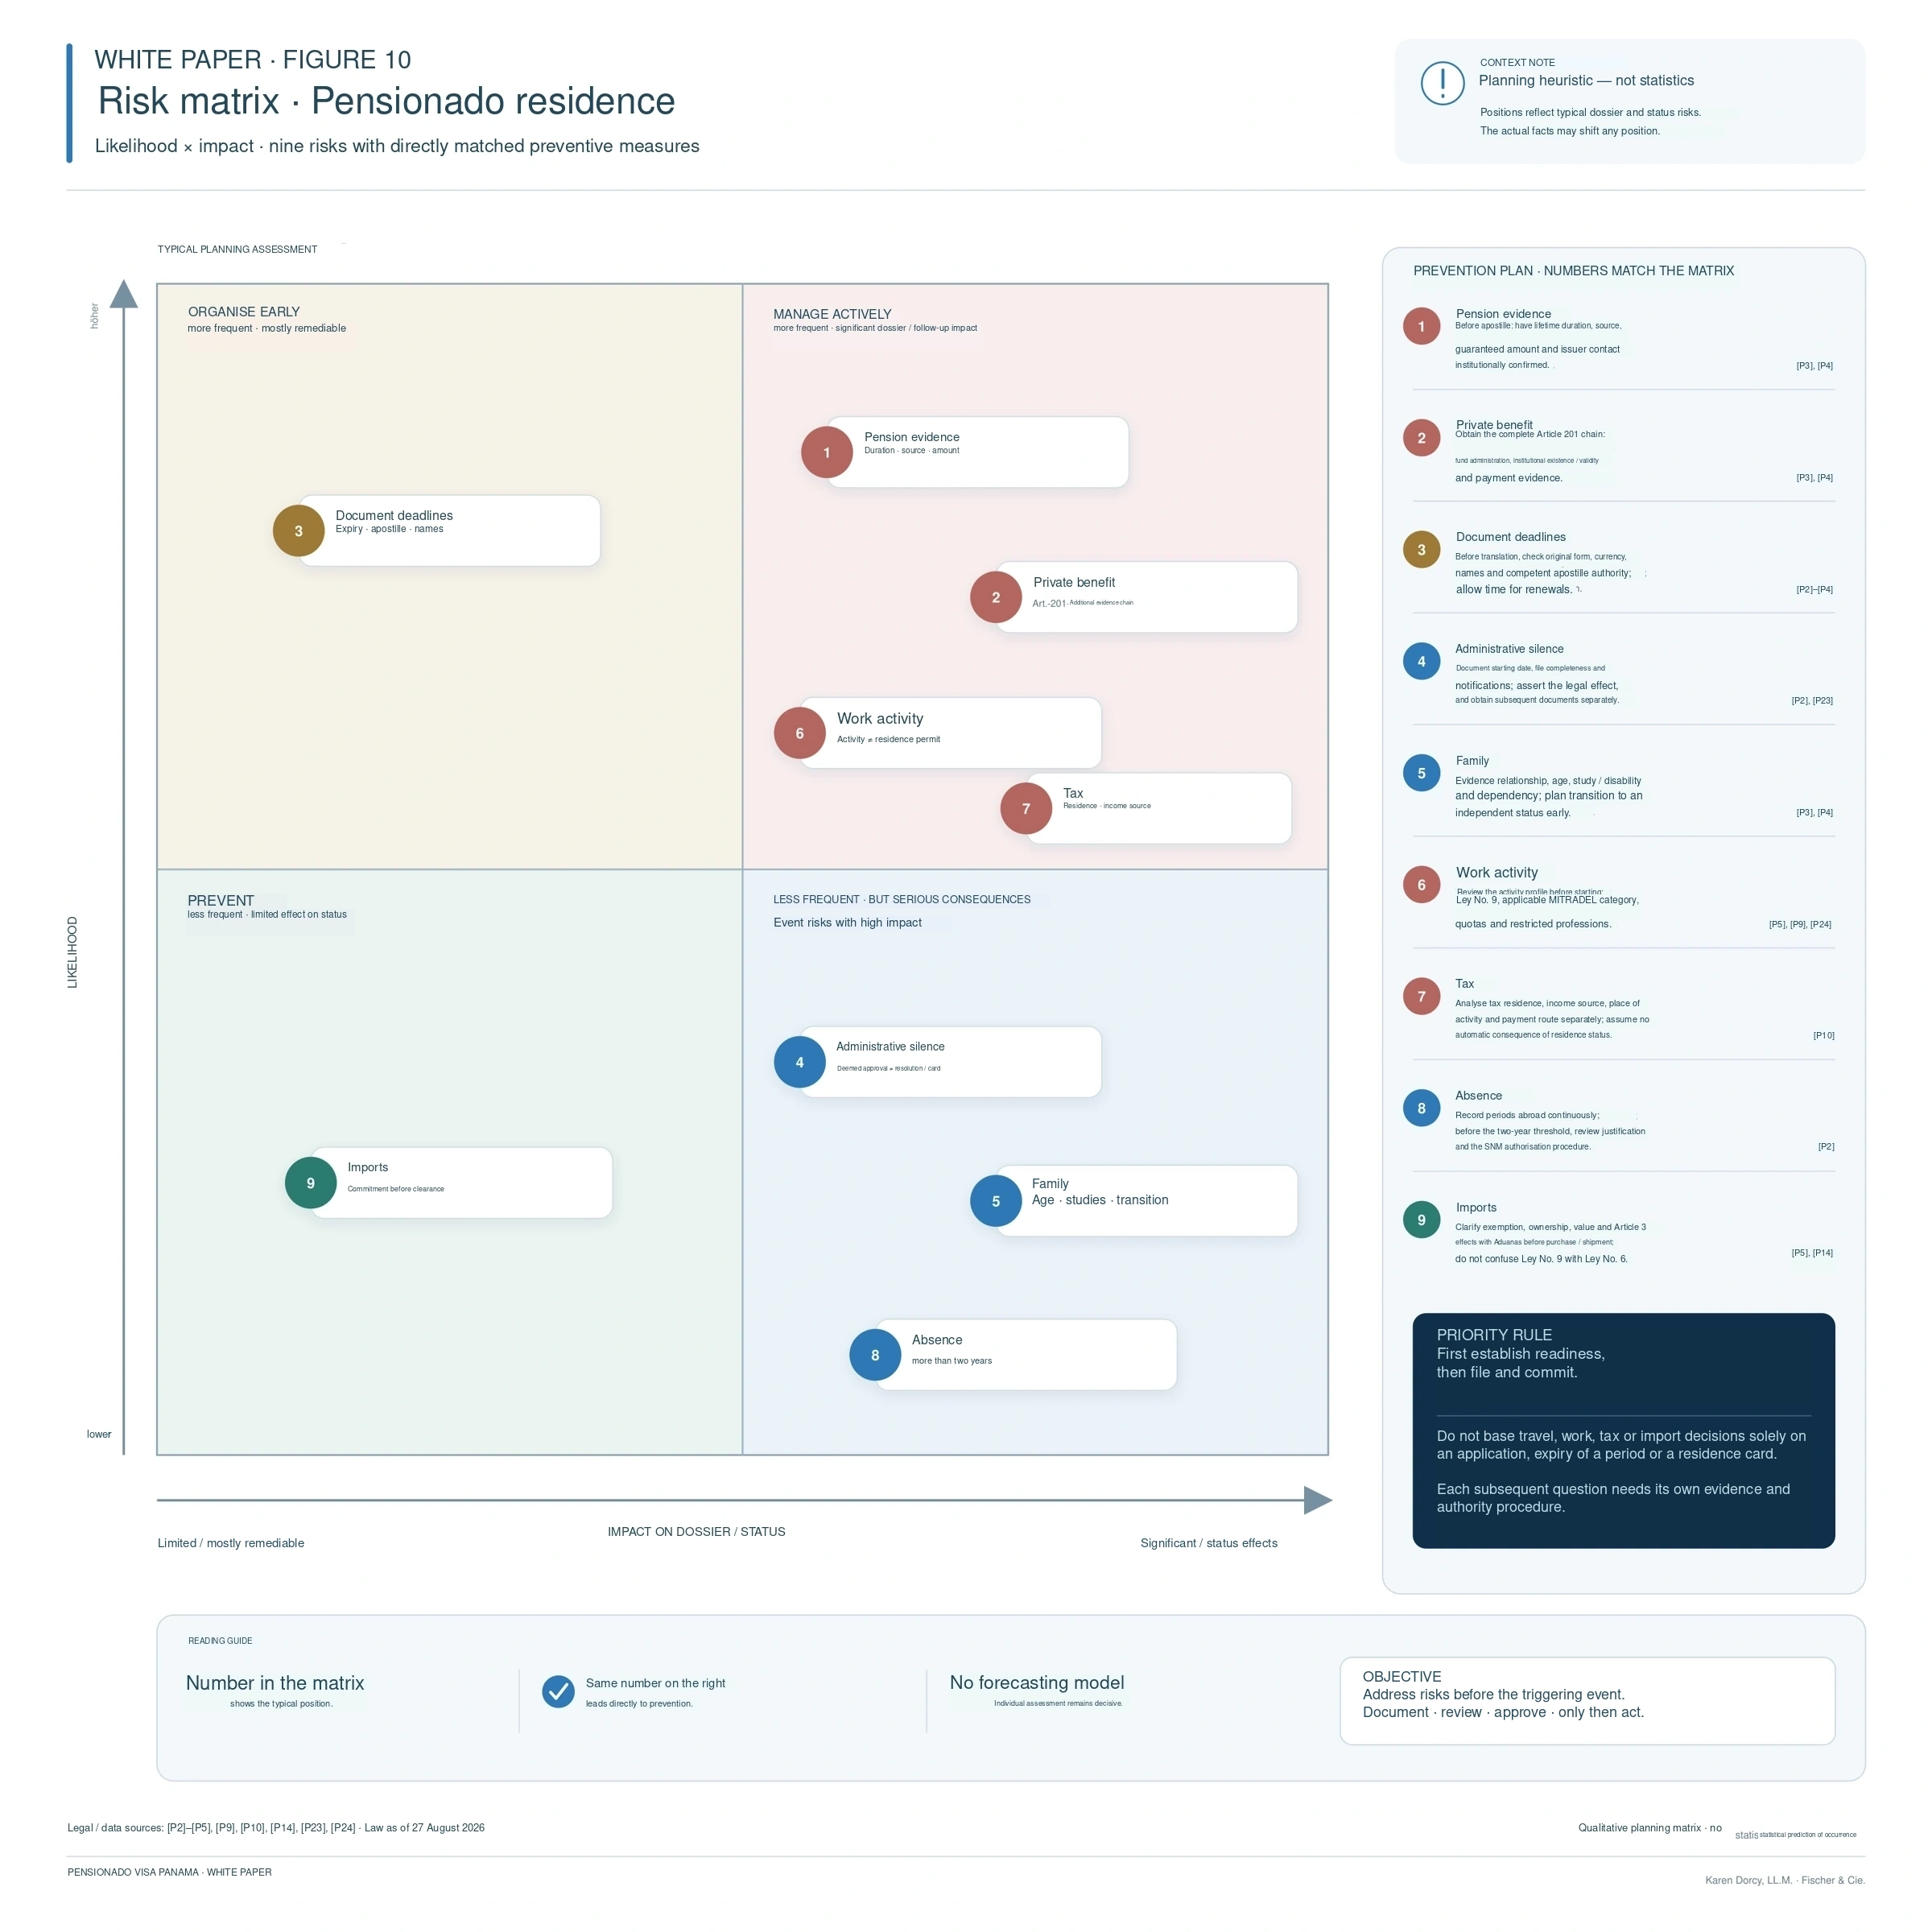
12.1 Risk matrix
Table 19 · Legal and procedural risk matrix
| Risk | Early warning | Impact | Response |
|---|---|---|---|
| Lifetime duration unclear | Certificate shows only a current payment or guarantee period. | High | Obtain institutional confirmation of duration before authentication and translation. |
| Incomplete private-pension evidence | Only an insurance policy or employer letter is available. | High | Complete Article 201 evidence of fund administration, existence/validity and payment. |
| Pension close to the threshold | Foreign currency or variable components without a margin. | Medium to high | Document conversion and guaranteed minimum; no exchange-rate assurance. |
| Property exception overstated | Corporate ownership, purchase option or value exactly B/.100,000. | High | Check personal registered title and value above the threshold. |
| Family status planned incorrectly | A student child is treated as a permanent resident. | High | Record status, age, study and a future independent route. |
| Defective document chain | Apostille on an unsuitable copy; inconsistent names. | High | Approve original form and data before translation. |
| Travel / timing promises | Filing is confused with the whole project. | Medium | Separate phases, dependencies and personal steps clearly. |
| Activity classified incorrectly | Remote work or a company role is described as automatically permitted. | High | Document the activity and assess Ley No. 9 / MITRADEL before starting. |
| Automatic tax assumptions | Residence or an overseas account is treated as a complete tax answer. | High | Assess residence and income source separately. |
| Extended absence | The two-year threshold is considered only after it is exceeded. | High | Document time abroad and clarify authorisation early. |
| Import arranged before clearance | Vehicle or household effects already purchased / shipped. | Medium to high | Confirm the Aduanas procedure before committing. |
12.2 Fact-checking common claims
Table 20 · Common claims assessed
| Claim | Legal assessment |
|---|---|
| “Pensionado residence is temporary.” | Incorrect for the principal category. Amended Article 203 provides indefinite residence without renewal; cancellation grounds remain. [P2], [P13] |
| “Anyone aged 55 or 60 can apply.” | Incorrect. The immigration category requires a qualifying lifetime pension, not merely age. Age criteria particularly concern Ley No. 6. [P3], [P14] |
| “B/.1,000 in an account is enough.” | Incorrect. Capital does not replace a lifetime pension from a qualifying source. [P3], [P4] |
| “Buying property removes the pension requirement.” | Incorrect. Personal property worth more than B/.100,000 only reduces the pension threshold to B/.750. [P3] |
| “Spouses may pool any income.” | Too broad. Article 201 permits combining their qualifying pensions. [P3] |
| “B/.250 per relative is paid to the government.” | Incorrect. It is additional monthly financial capacity, not a fee. [P4] |
| “Pensionados pay a B/.250 fee and B/.800 deposit.” | Incorrect for the regular Pensionado application: amended Article 201 excludes Article 28(4). [P2], [P5], [P13] |
| “Private annuities are always accepted.” | Unsupported. Private benefits require the additional fund-administration, existence/validity and payment evidence under amended Article 201. [P4], [P13] |
| “Nothing legally happens after 60 working days.” | Incomplete. Article 34 includes a positive administrative-silence mechanism, addressed by the official interpretation for applications from 26 August 2009. Application, enforcement and documents require separate assessment. [P2], [P23] |
| “Residence authorises employment and remote work.” | Incorrect as a general statement. Ley No. 9 and an applicable MITRADEL route require activity-specific review; permanent residence alone is not a generic work permit. [P5], [P9], [P24] |
| “Residence automatically creates tax residence.” | Incorrect. The DGI applies separate tax-residence criteria. [P18], [P19] |
| “Foreign income is always tax-free.” | Too broad. Source and tax treatment must be established for each income stream. [P10] |
| “Every concession applies automatically everywhere.” | Incorrect. Ley No. 6 defines beneficiaries, eligible services, conditions and evidence. [P14], [P15] |
| “A vehicle imported with relief can be sold immediately.” | Incorrect. Ley No. 9 contains disposal restrictions and possible recovery of duties. [P5] |
| “Permanent residence permits unlimited absence.” | Incorrect. Absence exceeding two years without the required justification or authorisation can lead to cancellation. [P2] |
| “Pensionado automatically leads to citizenship.” | Incorrect. Naturalisation is a separate constitutional and administrative process. [P1] |
Figure 10 · Risk matrix
13. Case studies: applying the legal analysis
These hypothetical examples illustrate the legal assessment. They are not accounts of client outcomes or predictions of approval.
Case 1 · State retirement pension above the threshold
The institutional certificate establishes entitlement, monthly amount and payment. Before filing, the lifetime duration is also checked. Criminal record, health certificate, authentication and translation follow. The case is supported by source, duration, amount and evidence—not by the country or scheme label alone. [P2]–[P4]
Case 2 · Foreign-currency pension just above B/.1,000
The pension is paid in a foreign currency. The file distinguishes certified amount, currency, payment frequency and traceable conversion. A narrow margin cannot be supported solely by a favourable historic exchange rate. Check the evidenced equivalent before filing. [P3], [P4]
Case 3 · Spouses with two pensions
Each spouse has a lifetime benefit. Article 201 permits combining qualifying pensions; each has a separate evidence record. A joint account or household income does not replace entitlement or duration evidence. Dependant status and additional financial capacity are checked against the SNM checklist. [P3], [P4]
Case 4 · Private insurance annuity
The contract provides a lifetime pension and a ten-year survivor guarantee. These are separate features. The insurer confirms the applicant’s lifetime entitlement, monthly amount and payment status. Fund administration, institutional existence/validity and payment evidence under amended Article 201 are also required. A brochure is insufficient. [P4], [P13]
Case 5 · Property and a B/.750 pension
The applicant owns registered property in Panama. Review personal ownership, acquisition and registry evidence, and a value exceeding B/.100,000. A lifetime pension of at least B/.750 remains necessary. Corporate ownership or exactly B/.100,000 must not be assumed sufficient. [P3], [P4]
Case 6 · A 23-year-old student child
The child needs family, dependency, full-time study and financial-capacity evidence. The file must expressly distinguish temporary child status from independent permanent Pensionado residence. Plan a later independent residence route in good time. [P3], [P4]
Case 7 · Consulting for foreign clients from Panama
“Remote” answers neither the employment nor tax question. Record services, location, clients, contract, subordination and remuneration, then assess Ley No. 9, any applicable MITRADEL route and income source. The Pensionado filing is not a work permit. [P5], [P9], [P10], [P24]
Case 8 · Death of the principal applicant
After approval, the principal applicant dies and the spouse may receive a survivor pension. Do not assume automatic transfer of status. Reassess the spouse’s entitlement, source, amount, lifetime duration, family status and the required SNM procedure. [P2], [P3]
Case 9 · Extended absence to care for a relative
A permanent resident plans several years abroad providing care. Assess departure and return against Article 31’s two-year rule. Review supporting justification and any authorisation route before exceeding the threshold; no blanket continuity guarantee is given. [P2]
Case 10 · Vehicle import after approval
Before purchase or shipment, confirm beneficiary status, vehicle, ownership, personal/family use, exemption procedure, shipping documents and disposal restrictions. Statutory tariff relief is not automatic customs clearance. [P5], [P12]
14. Frequently asked questions
Which pensions can qualify?
A lifetime jubilación or pensión from a foreign government, international organisation or private company. Private benefits require the additional amended Article 201 evidence. See Chapter 2. [P3], [P4], [P13]
Can a government retirement pension qualify?
It may fall within the expressly recognised government-source category. Institutional evidence of the applicant’s own entitlement, current monthly amount and lifetime duration is decisive.
Are US, UK and Canadian pensions automatically accepted?
No automatic country-based acceptance is asserted. Apply the Panamanian test to the actual benefit: provider, entitlement, duration, amount and authentication must be evidenced clearly.
Can private annuities qualify?
Potentially, where the benefit lasts for life and the additional Article 201 fund-administration, existence/validity and payment evidence is complete. The product name is insufficient. [P4], [P13]
Is a future pension promise enough?
A forecast or future entitlement is not equivalent to a pension currently payable for life. Filing requires current entitlement and payment evidence.
Must I be retired or meet a minimum age?
The immigration rule contains no general age limit but requires a demonstrated lifetime pension. The 55/60 age thresholds particularly concern Ley No. 6, not the residence test.
How large must the pension be?
Generally B/.1,000 monthly or its equivalent. Personal ownership of Panama property worth more than B/.100,000 may reduce the threshold to B/.750. [P3], [P4]
Can I combine several pensions of my own?
Article 201 expressly addresses combining spouses’ pensions. Several benefits of one applicant should be assessed individually for source, duration and acceptance under the current filing requirements.
What applies to spouses?
Spouses may combine qualifying pensions. Marriage evidence, personal details and additional dependant financial capacity still require review. [P3], [P4]
What does B/.250 per dependant mean?
Additional monthly financial capacity under the checklist, evidenced by additional pension or a local bank reference. It is not a government payment. [P4]
Can children be included?
Subject to dependency, age and evidence. The special rule for full-time students provides temporary status up to 25; children with a documented severe disability require separate consideration. [P3], [P4]
Must I buy property in Panama?
No. The standard route uses a B/.1,000 pension. Property is only an alternative that reduces the pension threshold.
Must my pension be paid into a Panamanian account?
The reviewed category does not generally require this. Private pensions do require payment evidence or a bank statement. Bank acceptance remains a separate KYC assessment.
Which documents need authentication and translation?
Assess each foreign document and issuing country. Establish the original form and competent authentication authority before translation. Chapter 4 provides the international coordination matrix.
How recent must the health certificate be?
Article 28 requires issue within three months before filing. Other documents do not automatically share that period. [P2]
How many trips to Panama are required?
There is no reliable universal number. Filing, lawful entry, identity and card procedures and current authority practice determine personal attendance.
How long does the procedure take?
Article 34 specifies up to 60 working days for a decision and 15 working days to remedy deficiencies. Its deemed-approval mechanism requires separate assessment. Enforcement, resolution, cards and the entire project timetable must be distinguished. [P2], [P23]
Are the B/.250 application payment and B/.800 deposit payable?
Not as regular Pensionado items. Amended Article 201 excludes this category from Article 28(4); Ley No. 9 also contains an immigration-related exemption. [P2], [P5], [P13]
May I work in Panama?
Not solely because of Pensionado residence. Assess the activity, Ley No. 9, an applicable MITRADEL category and any restricted profession. Permanent residence alone must not be treated as a generic work permission. [P5], [P9], [P24]
Is remote work for foreign clients permitted?
“Remote” is not a Pensionado authorisation. Assess the working relationship, place of performance, professional rules and income source before starting.
Does residence automatically make me taxable in Panama?
No automatic conclusion follows. Tax residence and income source have their own rules and procedures. DGI guidance includes a day-count connection among the relevant criteria. [P18], [P19]
Which benefits actually apply?
Ley No. 9 addresses certain import and immigration exemptions. Ley No. 6 grants concessions to its own beneficiary group. Eligibility, evidence and the particular transaction must each meet the applicable conditions.
Can I import household goods or a vehicle duty-free?
Ley No. 9 provides a one-time household/personal-effects tariff privilege up to B/.10,000 and a vehicle privilege on a two-year cycle. Confirm the Aduanas procedure before purchasing or shipping. [P5], [P12]
Must I live in Panama continuously?
Article 31 is not presented as an annual minimum-days quota. However, absence exceeding two years without the necessary justification or authorisation can lead to cancellation. [P2]
What if my pension provider changes?
Assess the new entitlement’s source, amount and lifetime duration. Because Article 31 addresses loss of the grounds for approval, review status before treating the change as purely administrative.
What happens if the principal applicant dies?
There is no blanket automatic transfer. Review dependent status, the survivor’s own benefit and any independent residence route promptly.
Does Pensionado lead automatically to citizenship?
No. Naturalisation is a separate constitutional and administrative process with additional requirements. [P1]
15. Legal conclusions
The Pensionado category centres on a defined lifetime benefit. A sound application nevertheless depends on more than the monthly amount: institutional classification, lifetime duration, private-pension evidence under Article 201, family roles, authenticated foreign documents and filing readiness all matter.
A reliable file separates immigration eligibility, documentary proof, employment law, tax law, and banking/customs procedures. None can be replaced by a marketing shortcut. Status management after approval is equally important: pension, family, address, absence and activity remain legally relevant.
The lawyer’s task is to provide a reasoned legal assessment, a controlled evidence chain and clear communication of unresolved matters—not an approval guarantee. International applicants also need timely coordination with advisers in the relevant foreign jurisdictions, whose legal disciplines remain outside the Panamanian engagement.
Appendix A · Pre-filing master checklist
Table 21 · Pensionado filing master checklist
| ID | Control | Status | Evidence / note |
|---|---|---|---|
| A01 | Pension source falls within the eligible categories | ||
| A02 | Lifetime duration institutionally confirmed | ||
| A03 | Monthly amount, currency and payment frequency clear | ||
| A04 | Current payment evidence available | ||
| A05 | Private evidence of fund administration, existence/validity and payment complete | ||
| A06 | Property exception used only for personal ownership above B/.100,000 | ||
| A07 | Spouses’ combined pensions and dependant roles assessed separately | ||
| A08 | Additional B/.250 monthly financial capacity per dependant evidenced | ||
| A09 | Children’s status, study and age limit documented | ||
| A10 | Passport details consistent across documents | ||
| A11 | Criminal record: relevant country and original form confirmed | ||
| A12 | Health certificate within the three-month period | ||
| A13 | Civil-status documents complete | ||
| A14 | Correct authentication authority for each document | ||
| A15 | Translation matched to the final original and apostille | ||
| A16 | Power of attorney and application finally reviewed | ||
| A17 | Lawful entry and personal attendance steps planned | ||
| A18 | SNM checklist rechecked on filing day | ||
| A19 | Cost categories and payment character distinguished | ||
| A20 | Employment / remote work / company role assessed separately | ||
| A21 | Tax and foreign-law advice arranged separately | ||
| A22 | Bank / KYC evidence consistent | ||
| A23 | Imports arranged only after current Aduanas review | ||
| A24 | Second-person check of names, dates, amounts and sources |
Appendix B · Budget worksheet
Table 22 · Budget without invented flat figures
| Item | Amount / currency | Recipient | Due date | Legal character / assumption |
|---|---|---|---|---|
| General Article 28 payment: B/.250 | exempt | Tesoro Nacional | — | Do not budget as a Pensionado charge under amended Article 201. |
| General Article 28 deposit: B/.800 | exempt | SNM | — | Do not budget as a Pensionado deposit under amended Article 201. |
| Overseas documents | ||||
| Apostilles / legalisations | ||||
| Translations | ||||
| Notary / register / courier | ||||
| Card / identity procedures | Confirm before the procedure. | |||
| Travel / accommodation | ||||
| Professional fee | Separate engagement scope, taxes and disbursements. | |||
| Contingency for additional evidence | Not a fixed government charge. |
Appendix C · Maintaining your status
Table 23 · Status-maintenance checklist
| Event | Document | Review before action | Responsibility |
|---|---|---|---|
| Address / personal-data change | Date, new details and evidence | Form and notification deadline | SNM |
| Pension provider changes | Old/new provider, amount, duration and transition | Continuing grounds for approval | SNM / immigration review |
| Death of a spouse | Death certificate, own entitlement, family status | Independent residence basis | Immigration / family review |
| Extended absence abroad | Departure, expected duration and reason | Two-year rule and authorisation | SNM |
| Starting an activity | Tasks, place, contract and remuneration | Ley No. 9, MITRADEL, professional rules and taxation | MITRADEL / DGI / specialist advice |
| New company / corporate role | Shareholding, role and operational tasks | Employment, corporate and tax status | Specialist advice |
| Household goods / vehicle import | Goods / vehicle, value, ownership and shipment | Exemption and disposal restrictions | Aduanas |
| Tax-related change | Presence, income and places of activity | Residence and source | DGI / foreign tax adviser |
| Bank / transfer | Source of funds, purpose and beneficial owners | KYC / AML requirements | Bank |
Appendix D · Matters requiring individual confirmation
Table 24 · Matters requiring individual confirmation
| Open matter | Why no blanket statement is appropriate | Obtain before deciding |
|---|---|---|
| Wording of a foreign pension certificate | Providers use different awards and descriptions of duration. | Review the issuer’s draft or specimen before authentication. |
| Combined spouses’ pensions and dependant financial capacity | Article 201 and the checklist address distinct evidence requirements. | Family roles and current SNM filing procedure. |
| Property valuation / financing | The wording does not resolve every ownership or financing arrangement. | Registry certificate, acquisition deed, value and current acceptance. |
| Card, certificate and subsequent charges | Public pages do not necessarily describe every step. | Official confirmation immediately before the procedure. |
| Work-permit route | Ley No. 9 and MITRADEL Decreto Ejecutivo No. 6/2023 require activity-specific reconciliation. | Written activity profile and applicable category. |
| Remote work | No automatic Pensionado exception; work permission and income source require review. | Contracts, place of performance, subordination and actual conduct. |
| Customs clearance and remaining charges | Tariff relief does not answer every operational cost question. | Aduanas / customs-agent review before purchase or shipment. |
| Continuing pension evidence | The checklist concerns filing, not a universal periodic reporting schedule. | Document changes and confirm the current SNM procedure. |
| Death of the principal applicant | Dependent status and an independent survivor benefit are separate legal bases. | Death certificate and complete evidence of the survivor’s own pension. |
| Number of trips to Panama | Files, entry, identity and card procedures differ. | Plan the current procedure in writing before booking travel. |
Appendix E · Primary-source register
These references identify official legislation, consolidated source texts and competent authorities. The German source edition is dated 26 August 2026. The English adaptation does not imply that every historical source is a fully consolidated statement of current law. The SNM checklist and US, UK and Canadian authentication guidance were checked for this adaptation. General portals are not substitutes for specific filing instructions. Check amendments and authority requirements before a concrete application or reliance on a concession.
[P1] Constitución Política de la República de Panamá, official Asamblea text. Official source — Article 10: separate naturalisation framework.
[P2] Decreto Ley No. 3 de 22 de febrero de 2008, Gaceta Oficial No. 25986. Official source — General file, cancellation, deadlines, notifications and remedies.
[P3] Decreto Ejecutivo No. 320 de 8 de agosto de 2008, Gaceta Oficial No. 26104. Official source — Art. 200–203: Jubilado y Pensionado.
[P4] Servicio Nacional de Migración: Requisitos para Jubilado Pensionado (PRP-JP). Official source — Official PRP-JP filing checklist (PE2.pdf); no stated issue or revision date.
[P5] Ley No. 9 de 24 de junio de 1987, Gaceta Oficial No. 20835. Official source — Beneficiaries, imports, immigration exemptions and activities.
[P6] Gaceta Oficial Digital. Official source — Official publication platform and amendment monitoring.
[P7] Servicio Nacional de Migración. Official source — Authority portal and administrative information.
[P8] Dirección General de Ingresos – DGI. Official source — Official tax-administration portal.
[P9] Decreto Ejecutivo MITRADEL No. 6 de 13 de abril de 2023, Gaceta Oficial No. 29760-C. Official source — Work-permit framework. Check the decree and Gazette date rather than relying on a potentially misleading filename.
[P10] Ley No. 6 de 2 de febrero de 2005, Gaceta Oficial No. 25232. Official source — Article 13: basic Article 694 Código Fiscal wording on territoriality and source; not a complete current amendment consolidation.
[P11] Tribunal Electoral: Servicios de Cedulación. Official source — General official guidance for the separate identity-document procedure; not a Pensionado-specific checklist.
[P12] Autoridad Nacional de Aduanas: Gestión de Servicios y Trámites Aduaneros. Official source — Official procedures portal including valuation / exemptions; not a substitute for the legislation or a case-specific checklist.
[P13] Decreto Ejecutivo No. 26 de 2 de marzo de 2009, Gaceta Oficial No. 26238. Official source — Articles 53–54: Article 28(4) exception and indefinite residence.
[P14] Texto Único de la Ley No. 6 de 10 de junio de 1987, Gaceta Oficial No. 26314-A. Official source — Beneficiaries, concessions, evidence and enforcement; subsequent amendments require separate review.
[P15] ACODECO: official Ley No. 6 guidance. Official source — Administrative guidance, not a substitute for legislation.
[P16] Ley No. 192 de 23 de diciembre de 2020. Official source — Tax treatment of certain concessions.
[P17] Ley No. 36 de 2 de agosto de 2016. Official source — Separate additional age-related provisions.
[P18] DGI: Número Tributario (NT) Natural. Official source — Official guidance referring to a 183-day connection; not an exhaustive individual residence opinion.
[P19] DGI: Certificado de Residencia Fiscal. Official source — Official evidence requirements for the certificate.
[P20] United States government: authentication of US documents. Official source — Distinguishes state and federal apostille routes.
[P21] UK Government: get your document legalised. Official source — Legalisation Office, eligible UK documents and paper / electronic apostilles.
[P22] Global Affairs Canada: document authentication requirements. Official source — Federal and provincial responsibilities; check the actual issuing or notarising jurisdiction.
[P23] Procuraduría de la Administración, Consulta C-111-09, 3 September 2009. Official source — Official interpretation of Article 34 positive administrative silence for applications filed from 26 August 2009; application and enforcement remain case-specific.
[P24] MITRADEL: Migración Laboral – work-permit classification. Official source — Official category overview; do not infer a generic Pensionado work permission.
[P25] SERTV: official report on the veto of bills 226 and 594, 21 September 2026. Official source — Reports that bill 226 was objected to in its entirety; bill 594 was only partially objected to. Legislative proposals must be distinguished from enacted law.
Appendix F · Spanish–English glossary
Table 25 · Key Spanish legal terms
| Spanish term | English working translation | Note |
|---|---|---|
| Jubilado y Pensionado | Retired person / pensioner | Official category terminology. |
| Permiso de Residente Permanente | Permanent residence permit | Immigration status; separate from taxation and work. |
| Pensión vitalicia | Lifetime pension / annuity | Central eligibility requirement. |
| Dependiente | Dependant | Family and financial-capacity evidence required. |
| Poder / apoderado legal | Power of attorney / authorised legal representative | Filing through a legal representative. |
| Depósito de repatriación | Repatriation deposit | General Article 28 item; Pensionado exempt under amended Article 201. |
| Franquicia arancelaria | Customs-tariff exemption | Not equivalent to automatic exemption from every charge. |
| Paz y salvo | Clearance / no-outstanding-liability certificate | Context-specific official evidence; not a universal PRP-JP checklist item. |
| Apostilla | Apostille | Authentication of the formal origin of a public document. |
| Reconsideración / apelación | Reconsideration / appeal | Formal remedies with short deadlines. |
Author, citation and contact
Karen Dorcy, LL.M., is an Abogada of the Republic of Panama (Idoneidad No. 10179). Her work includes reviewing and supporting Panamanian residence applications, structuring evidence and coordinating with the competent Panamanian authorities. Advice is available in English, German and Spanish.
The engagement concerns the law of the Republic of Panama. This commentary does not advise on foreign law or recommend whether a person should relocate.
Table 27 · Authorship, edition and citation
| Publication detail | Contents |
|---|---|
| Author of the German source | Karen Dorcy, LL.M. · Abogada of the Republic of Panama · Idoneidad No. 10179 |
| Languages | English, German and Spanish |
| Publisher | Fischer & Cie. |
| Edition / source date | English adaptation of source edition 1.0, dated 26 August 2026 |
| Suggested citation | Dorcy, Karen, LL.M., “Panama Pensionado Visa: Legal Framework, Evidence and Procedure”, Fischer & Cie., English adaptation of German source edition 1.0 (26 August 2026), relevant chapter and source reference. |
| Subject matter | Panamanian residence law and directly related Panamanian administrative procedures; foreign law excluded. |
Author profile: Karen Dorcy at Fischer & Cie.
Service page: Panama Pensionado Visa
FISCHER & CIE. · LEGAL KNOWLEDGE FROM PANAMA
Dorcy, Karen: Panama Pensionado Visa. English legal commentary adapted from German source edition 1.0 dated 26 August 2026; cite the relevant chapter and source reference.
View the complete source register